


Reporting live from Gavin Baker’s TomorrowX conference. Know I’ve been a bit slow on the articles, but not for lack of research. As mentioned previously, sometimes my perfectionism gets in the way of frequency, and so with your empathy, we’re going to try to go back to at least two times a week, with a little more ‘wet clay’ as it were.
Mood at the conference is…interesting. Not a party, not a funeral. Something…in between. Kind of like a school reunion where a good friend just came down with a pretty gnarly illness. You can’t count them out, but it’s a long road back.
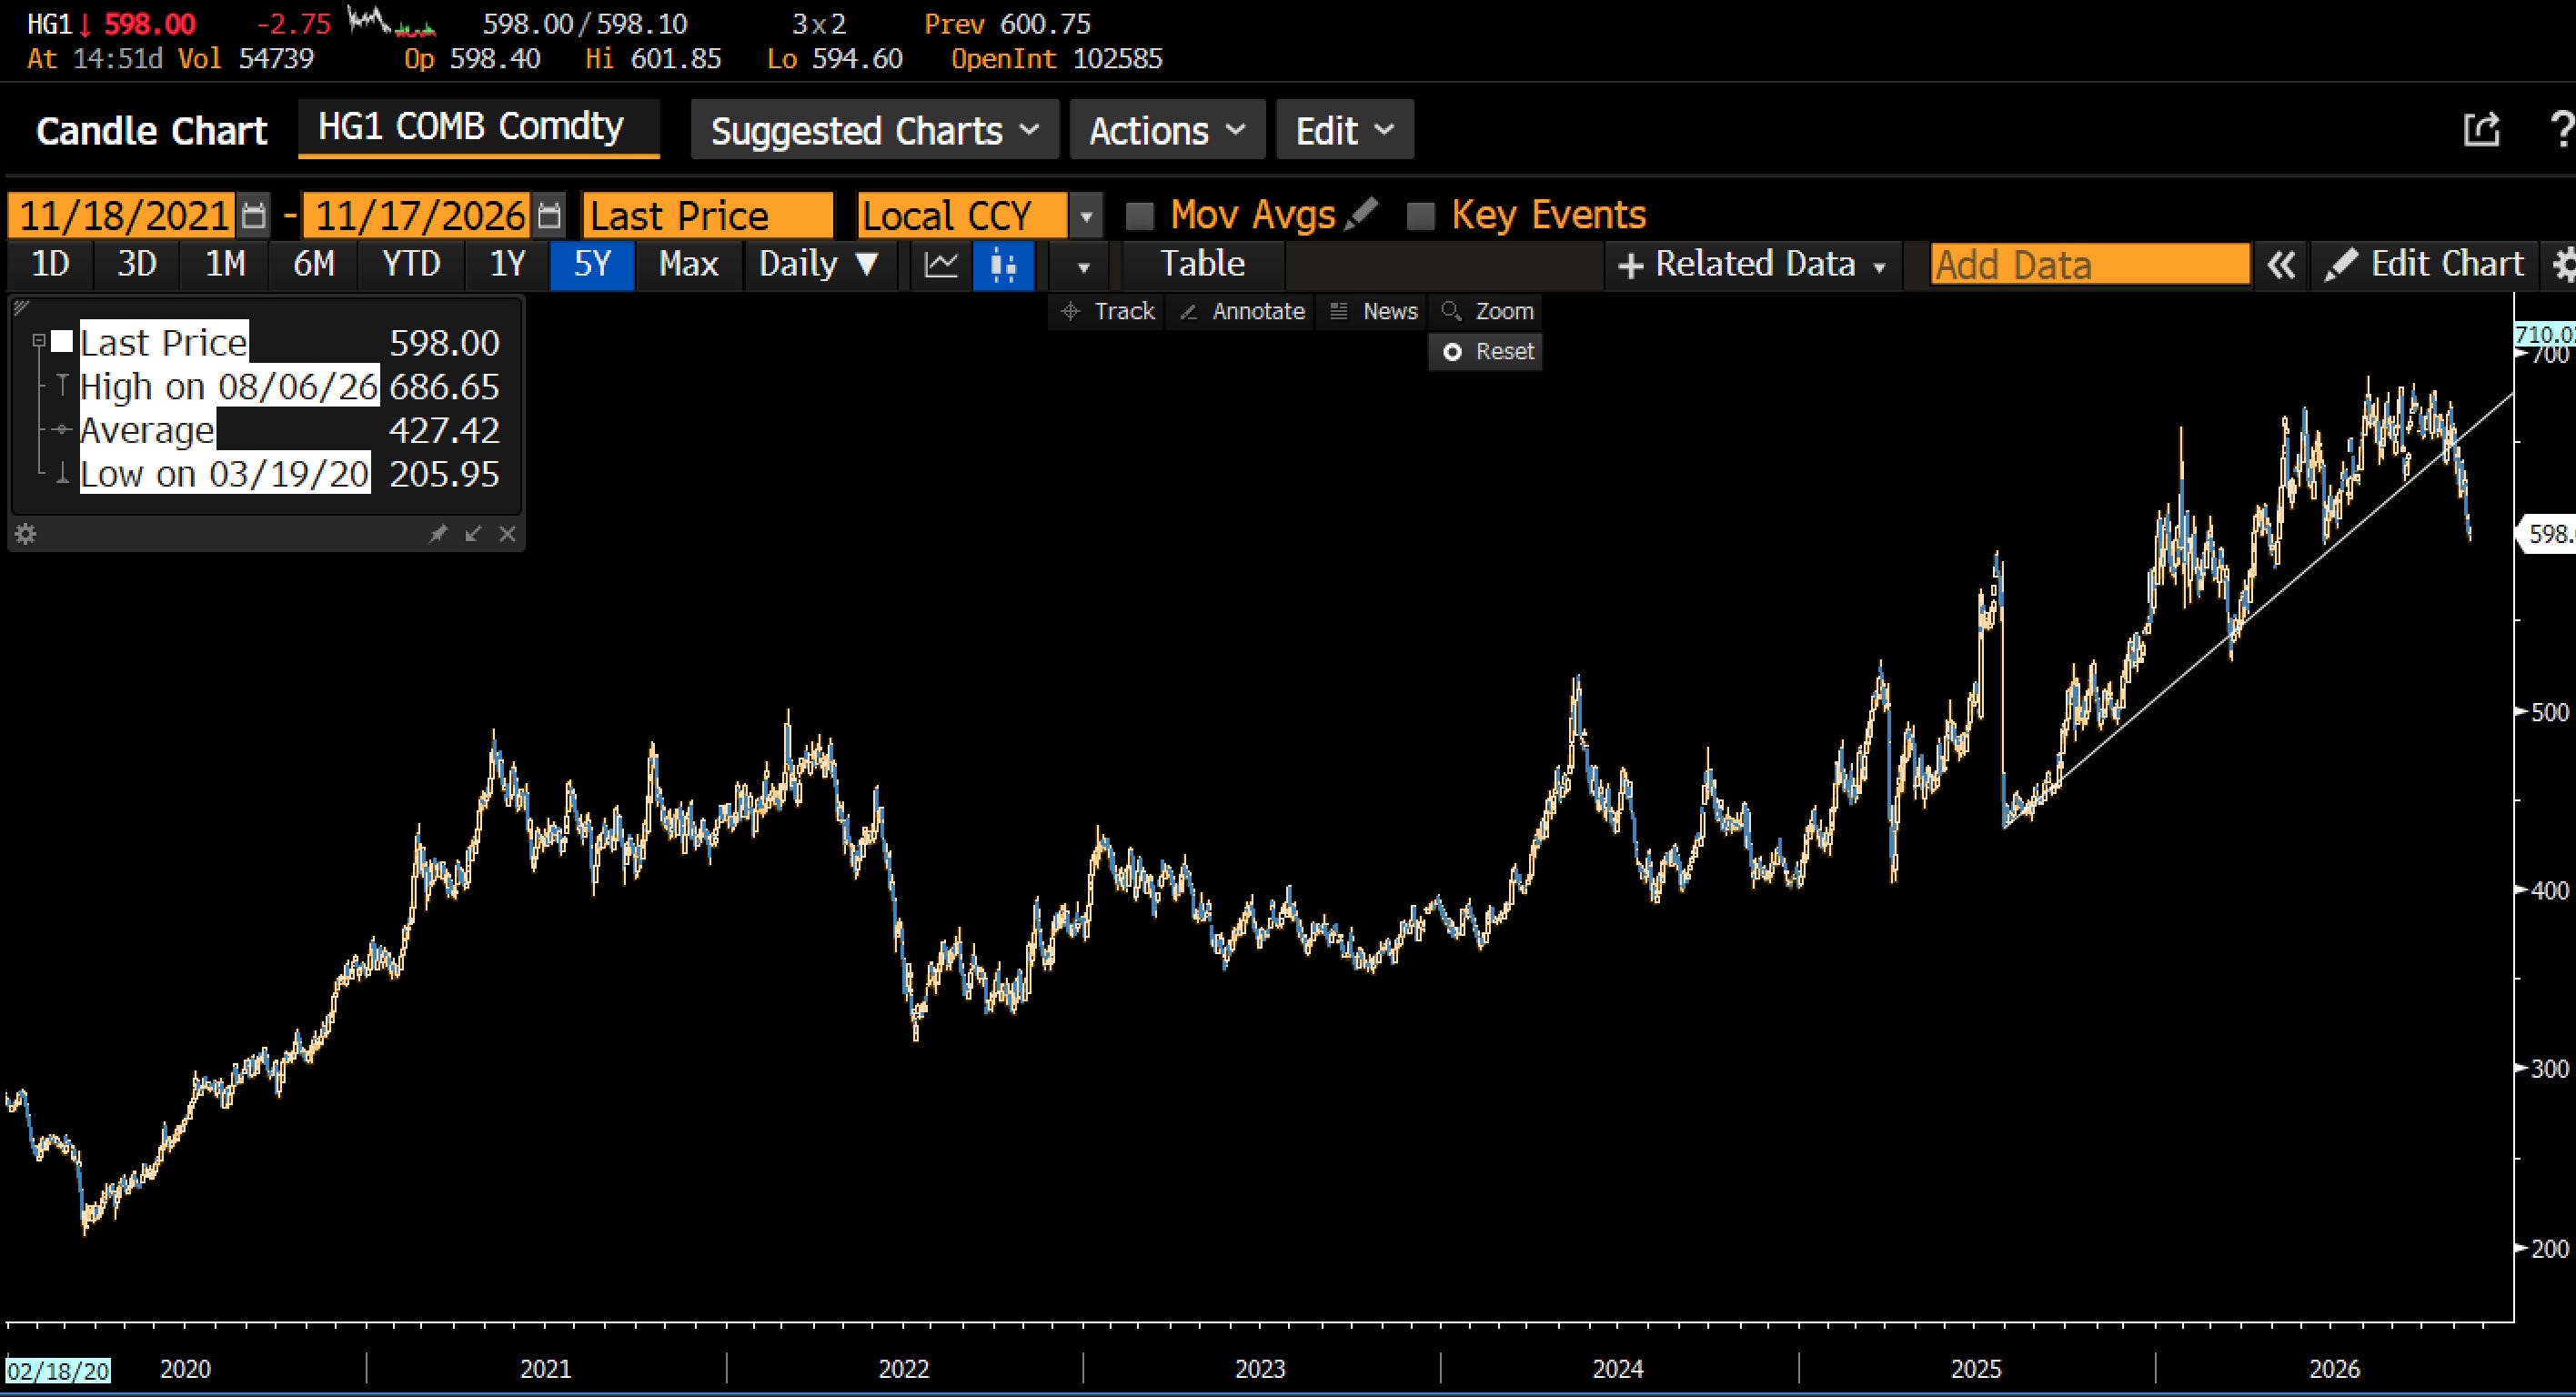
Druckenmiller just left the stage. Notably muted. Short copper,
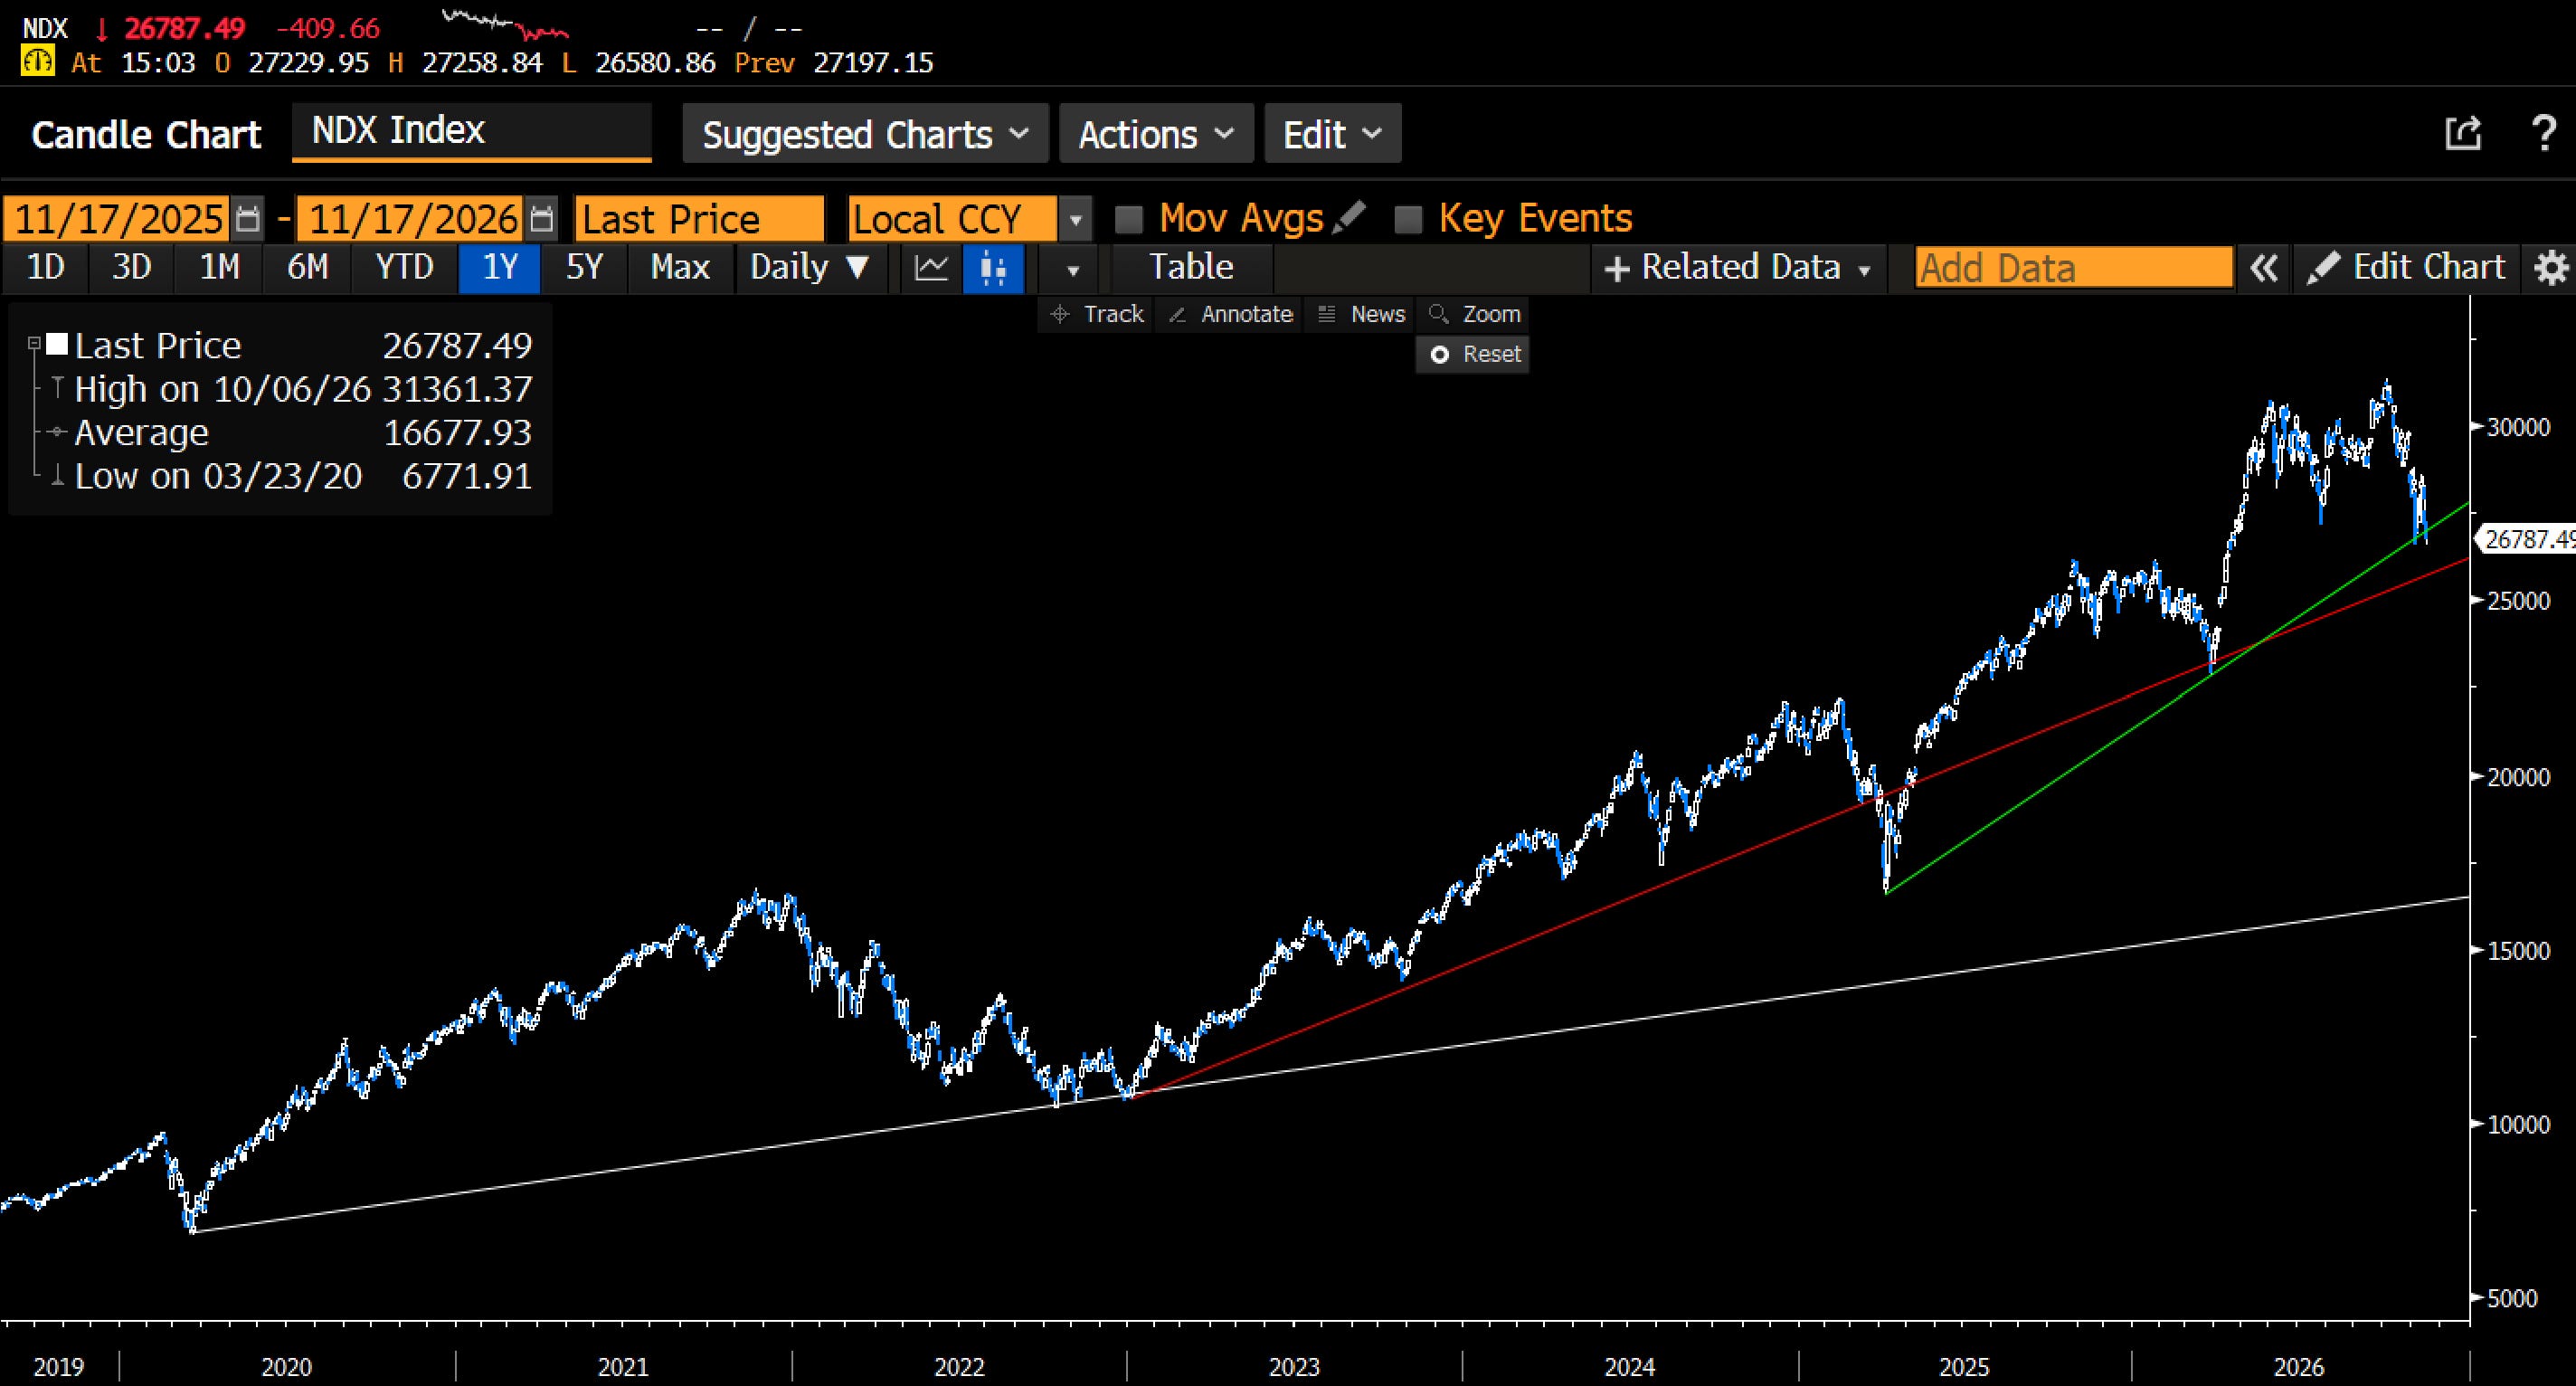
close to flat on stocks,
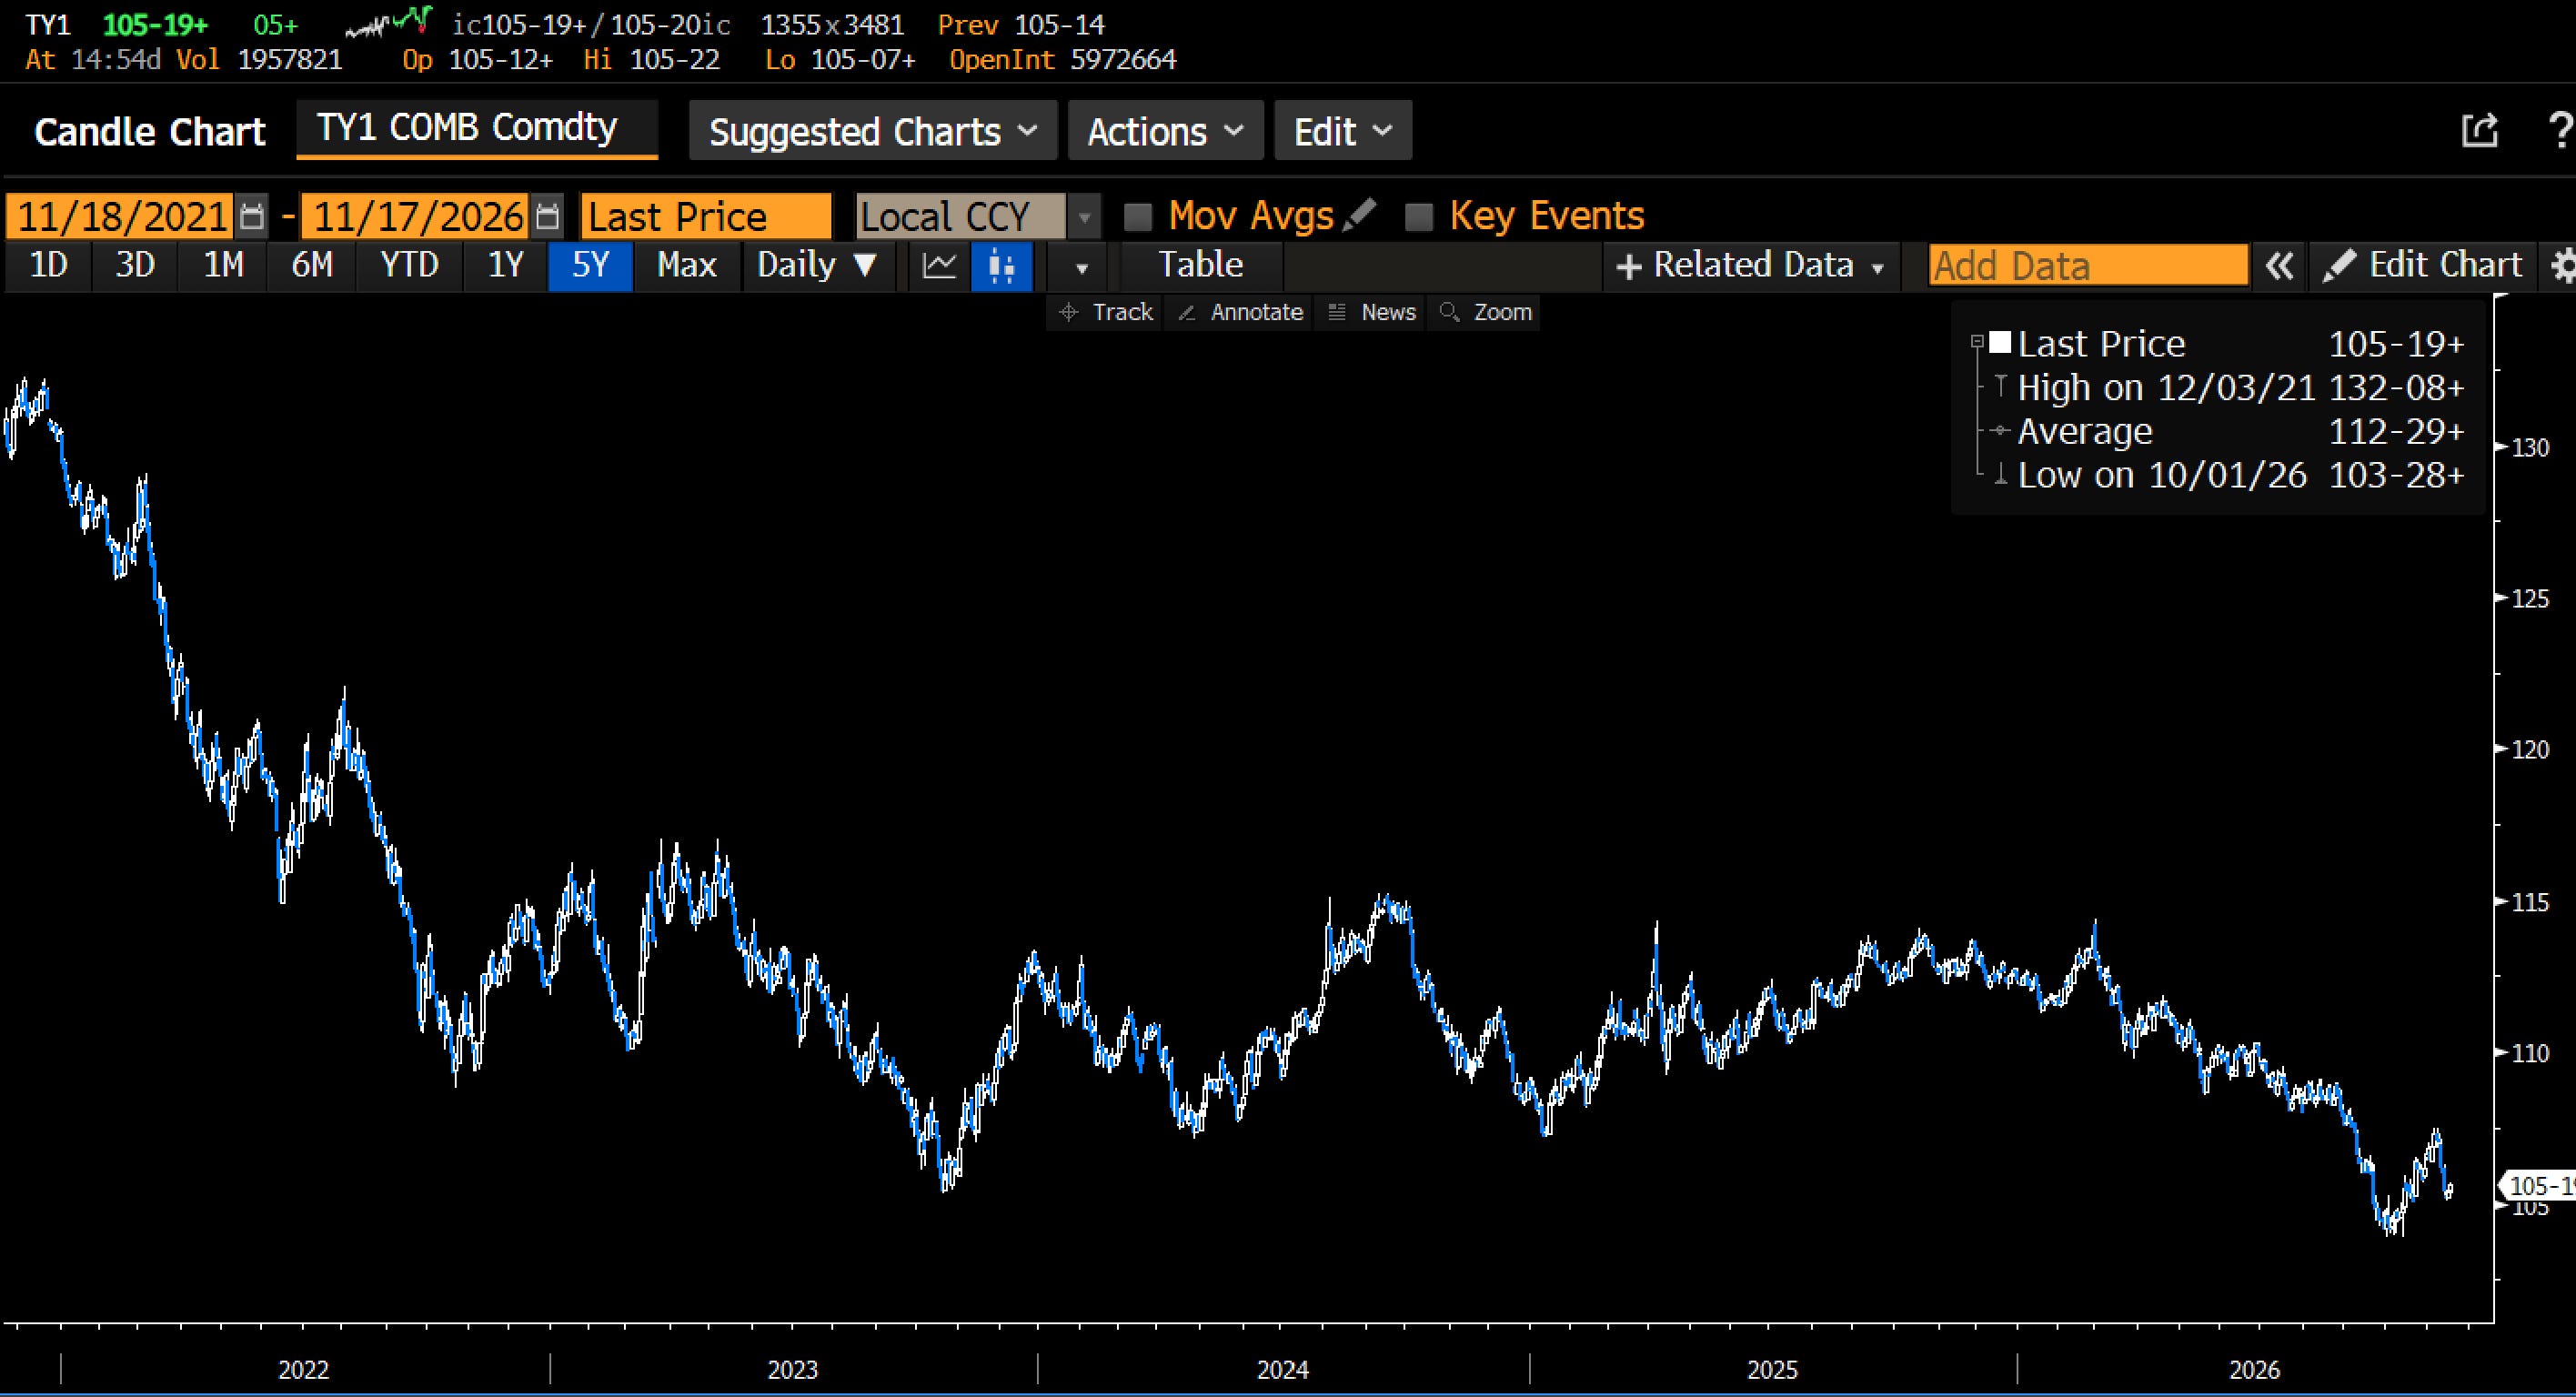
and with a growing appetite for bonds.
We didn’t get too caught up in the copper story. Never could model out the full demand and supply, and there’s so much demand going into opaque avenues like Chinese real estate and infrastructure that I didn’t want to touch it outside of having it for a bit of beta and portfolio balance. It just needed more work.
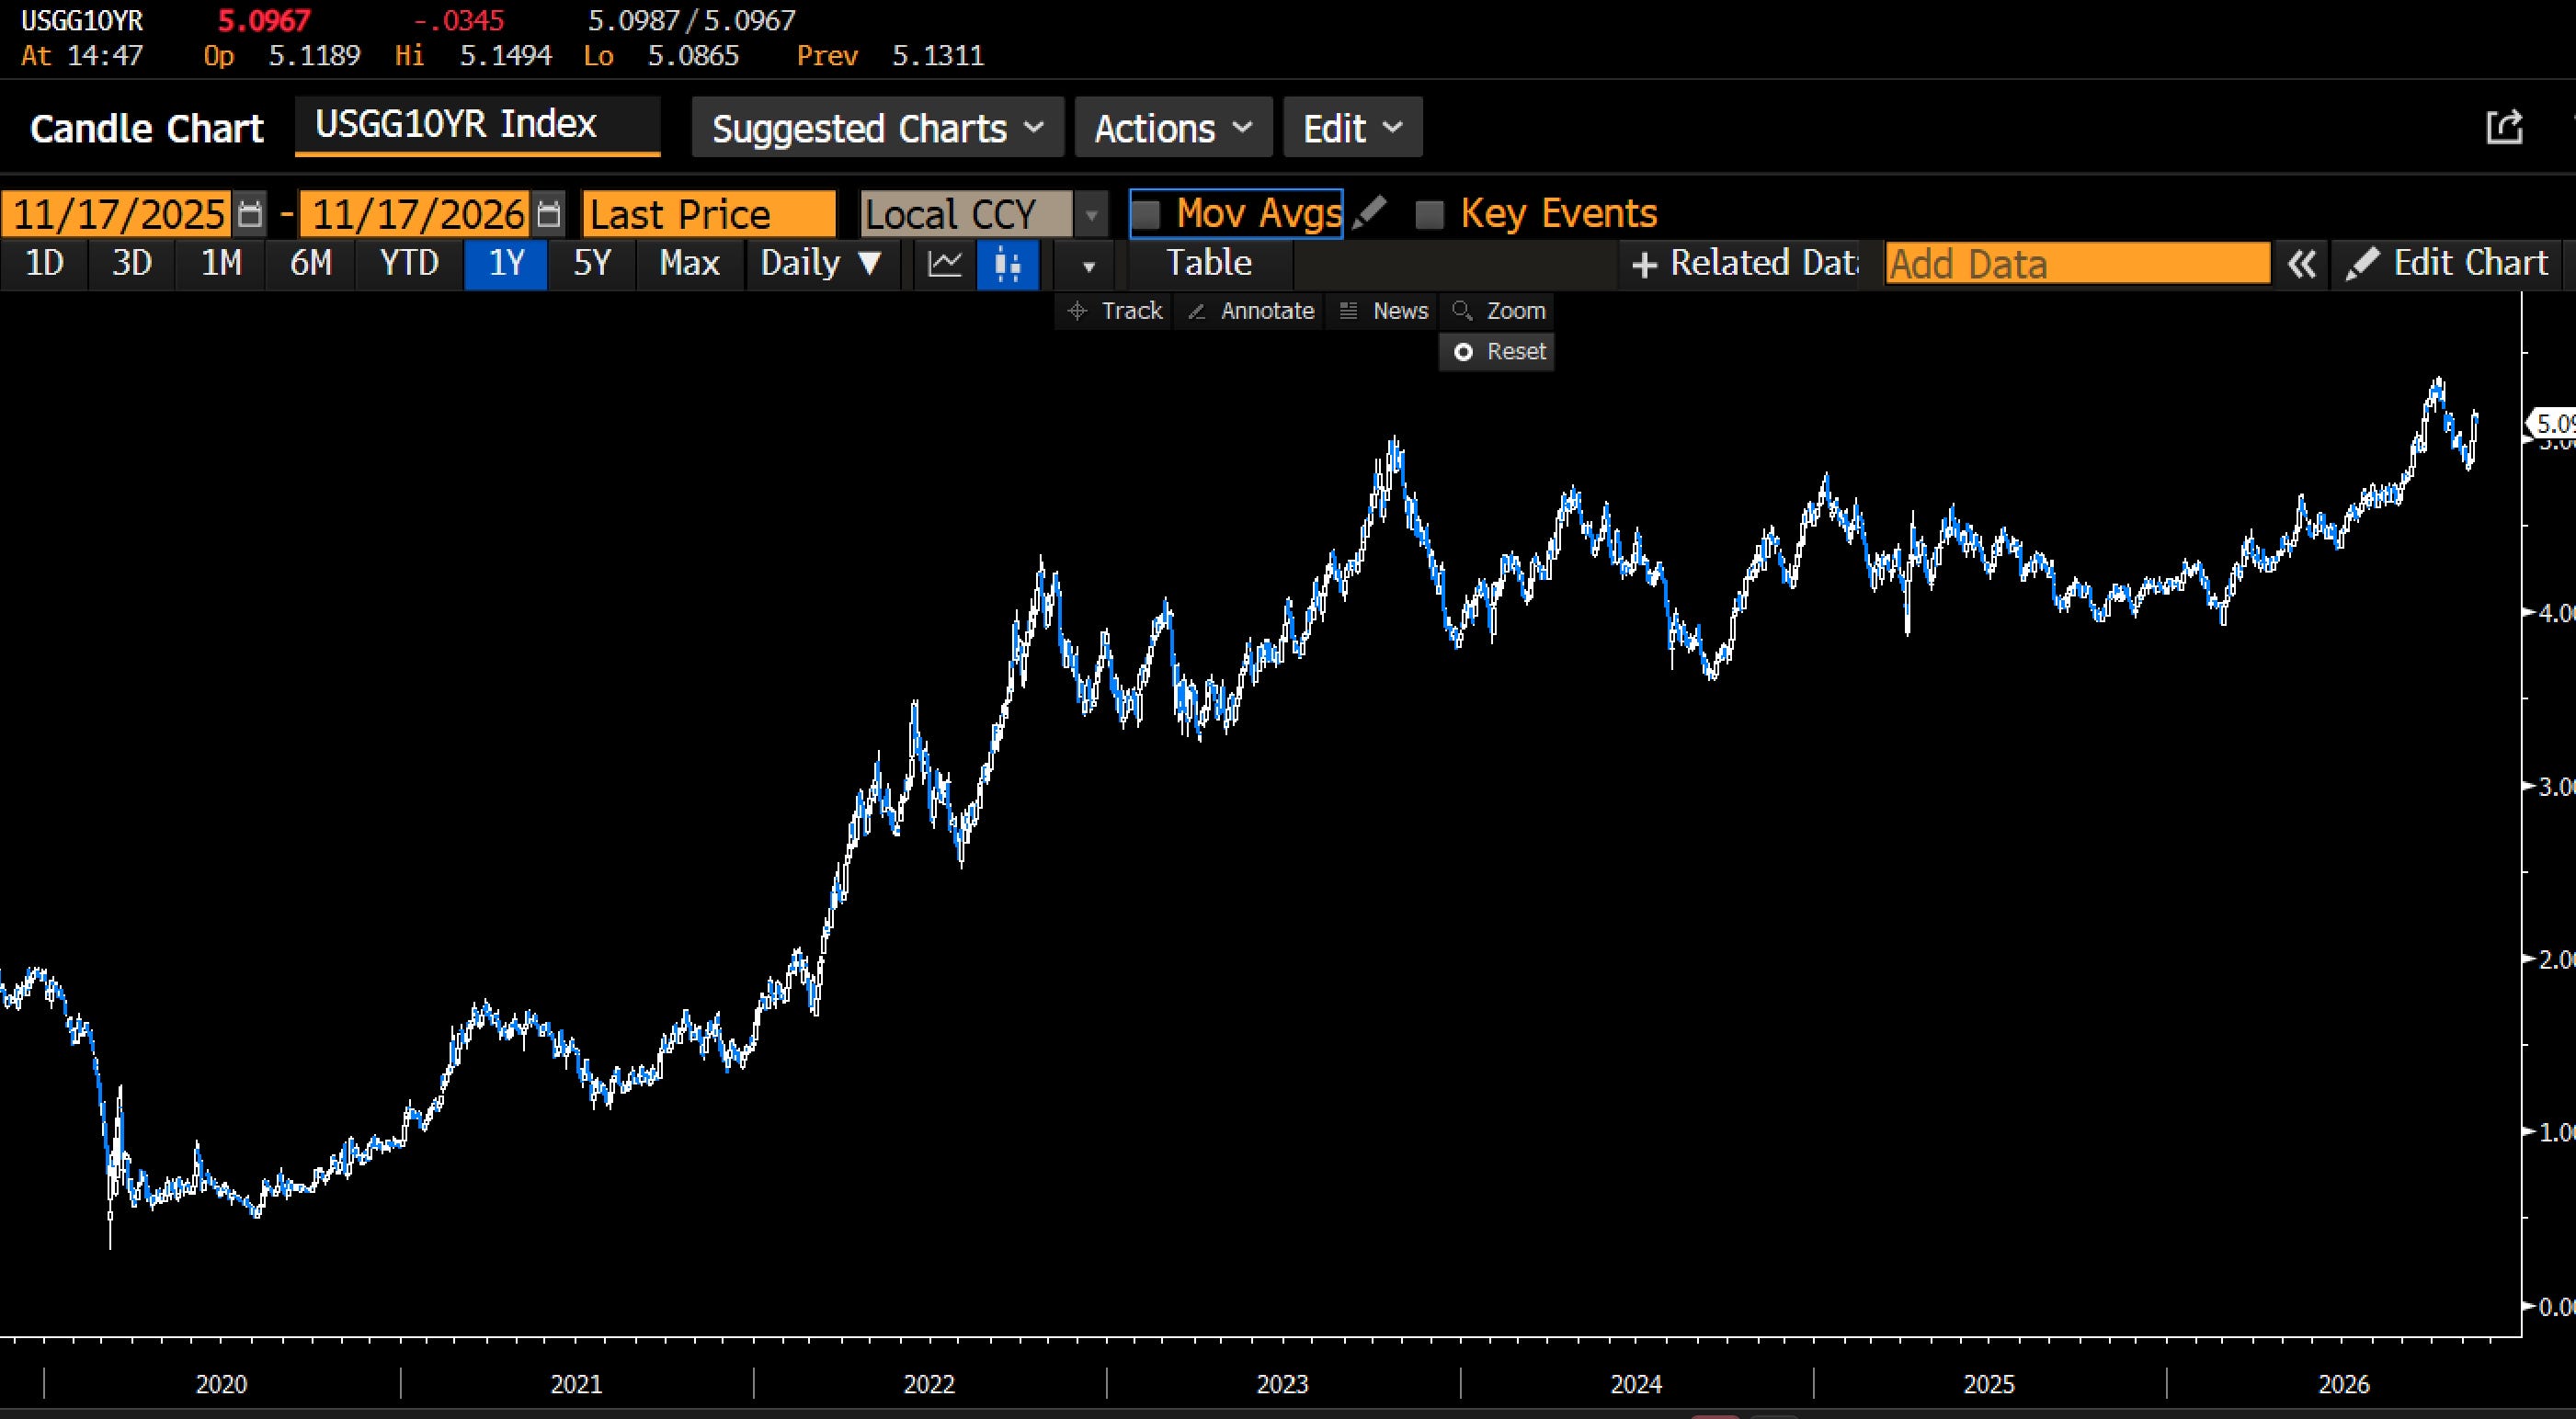
The scary part of Druckenmiller’s outlook above is the bonds. Yields don’t peak on vibes, they peak on economic expectations of inflation and tightening.
Well, we got the tightening, though it’s starting to do the thing where the curve flattens because front-end yields go up and the back end stalls, or in Germany’s case falls.
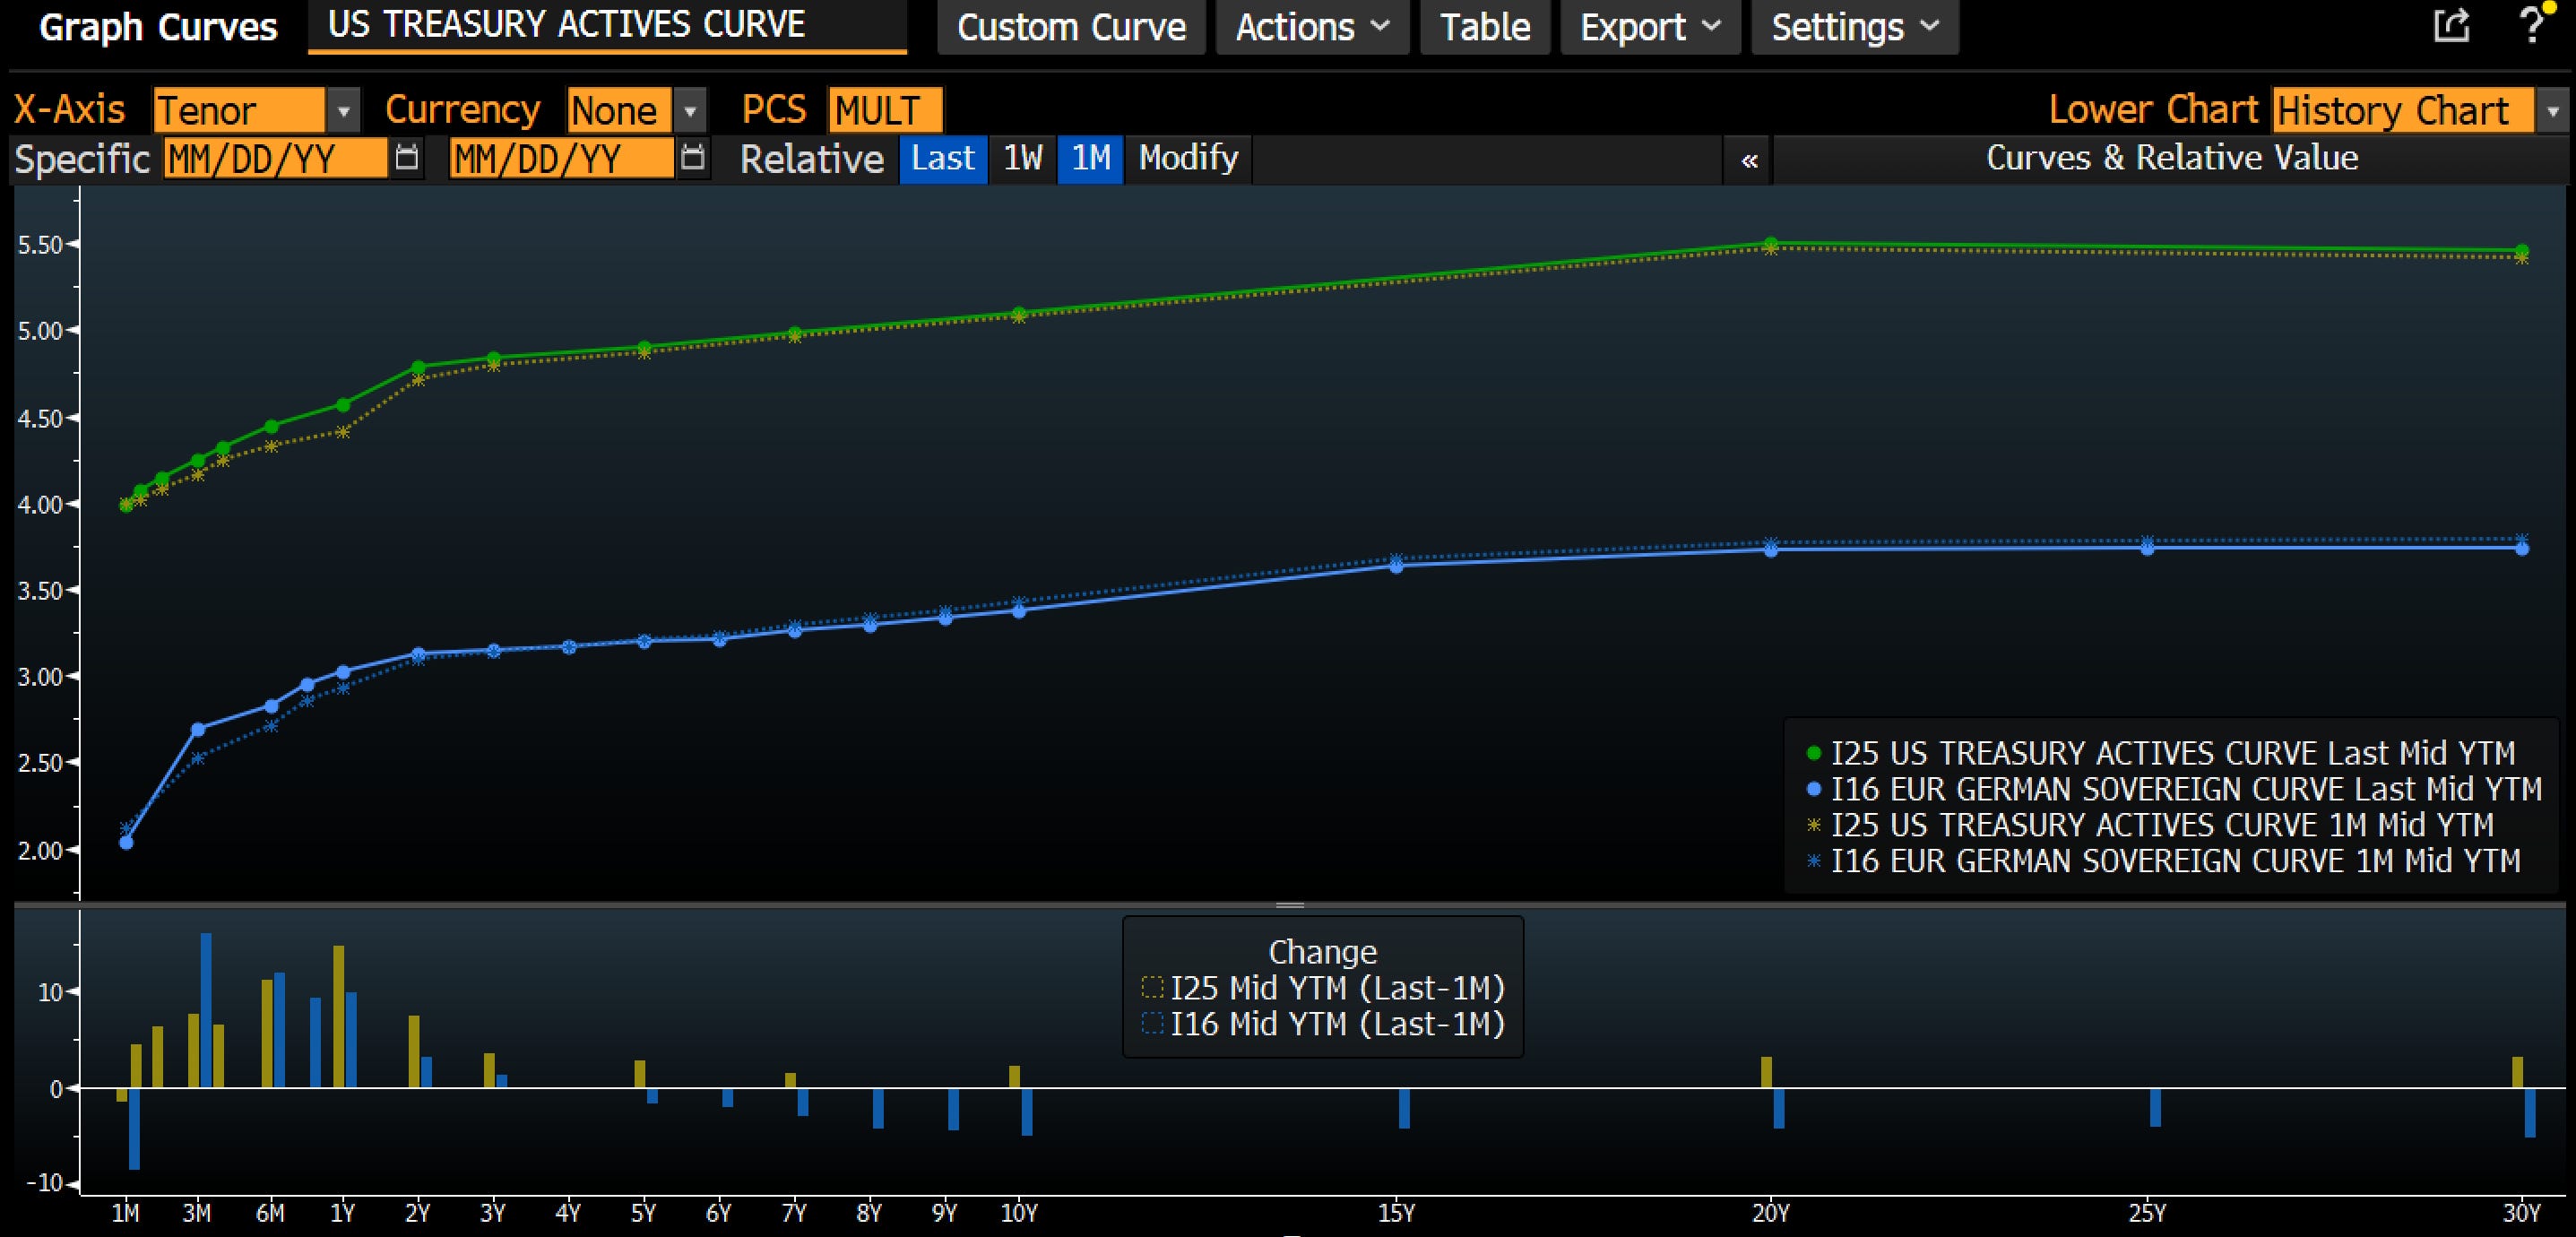
Which is what you see towards the end of cycles, when the market can’t really take much more tightening without cracking the growth engine.
Honestly, the feeling here is a little…hungover.
Some folks hit the infra wave, built a business or a summer home with the proceeds, and are still long but cashed out enough that their heart isn’t really in it.
Then there’s the old guard, who are a little pepped up by the return of financial sobriety. Ready to have their AI analysts run a million Excel files on why your next financing is going to be a little more challenging.
Next to the old guard is the emeritus class. A lot of them in fireside chat mode, where they aren’t really breaking stories or introducing technology, but telling old stories to new (potential) investors.
Most important for the future of the country, there is a new guard. Folks here building.
People trading compute. Folks hunting for innovations in the model or application layer. Robotics companies excited to energize the next generations of machines.
All these folks are slowly waking up to the fact that what happened to Jensen is an outcome of bigger priorities than your next earnings announcement. All against the backdrop of a seemingly endless array of machines ‘going down’: proactively (to patch critical systems), accidentally (as they push rushed code patches with bugs the machine coder missed) or unfortunately (as a defensive reaction to attack, or as part of a system being compromised).
An awareness that the AI build is about a lot more than 23-year-olds raising and making billions because of the bleep bloops. And an awareness that yes, the doomers were right about one thing: connecting the robots to the internet is inevitably going to open up a new world of security problems. What they may have gotten wrong is the reaction function of the humans, which is not to needlessly give agents MORE power, but to work on things like alignment, agentic monitoring and control, and even insurance and legal frameworks for the deployment of machine intelligence in the physical and financial world.
A lot of which boils down to what looks to me like tighter compute supply on a 1-3 year horizon. Tighter credit, as the CFO of Nvidia takes a magnifying glass to all those midnight dinner guarantees Jensen made. Tighter chip supply, at least to Asia, at least until China figures out the EUV machines. Likely tighter mineral supply in the West, as China retaliates for tighter chips.
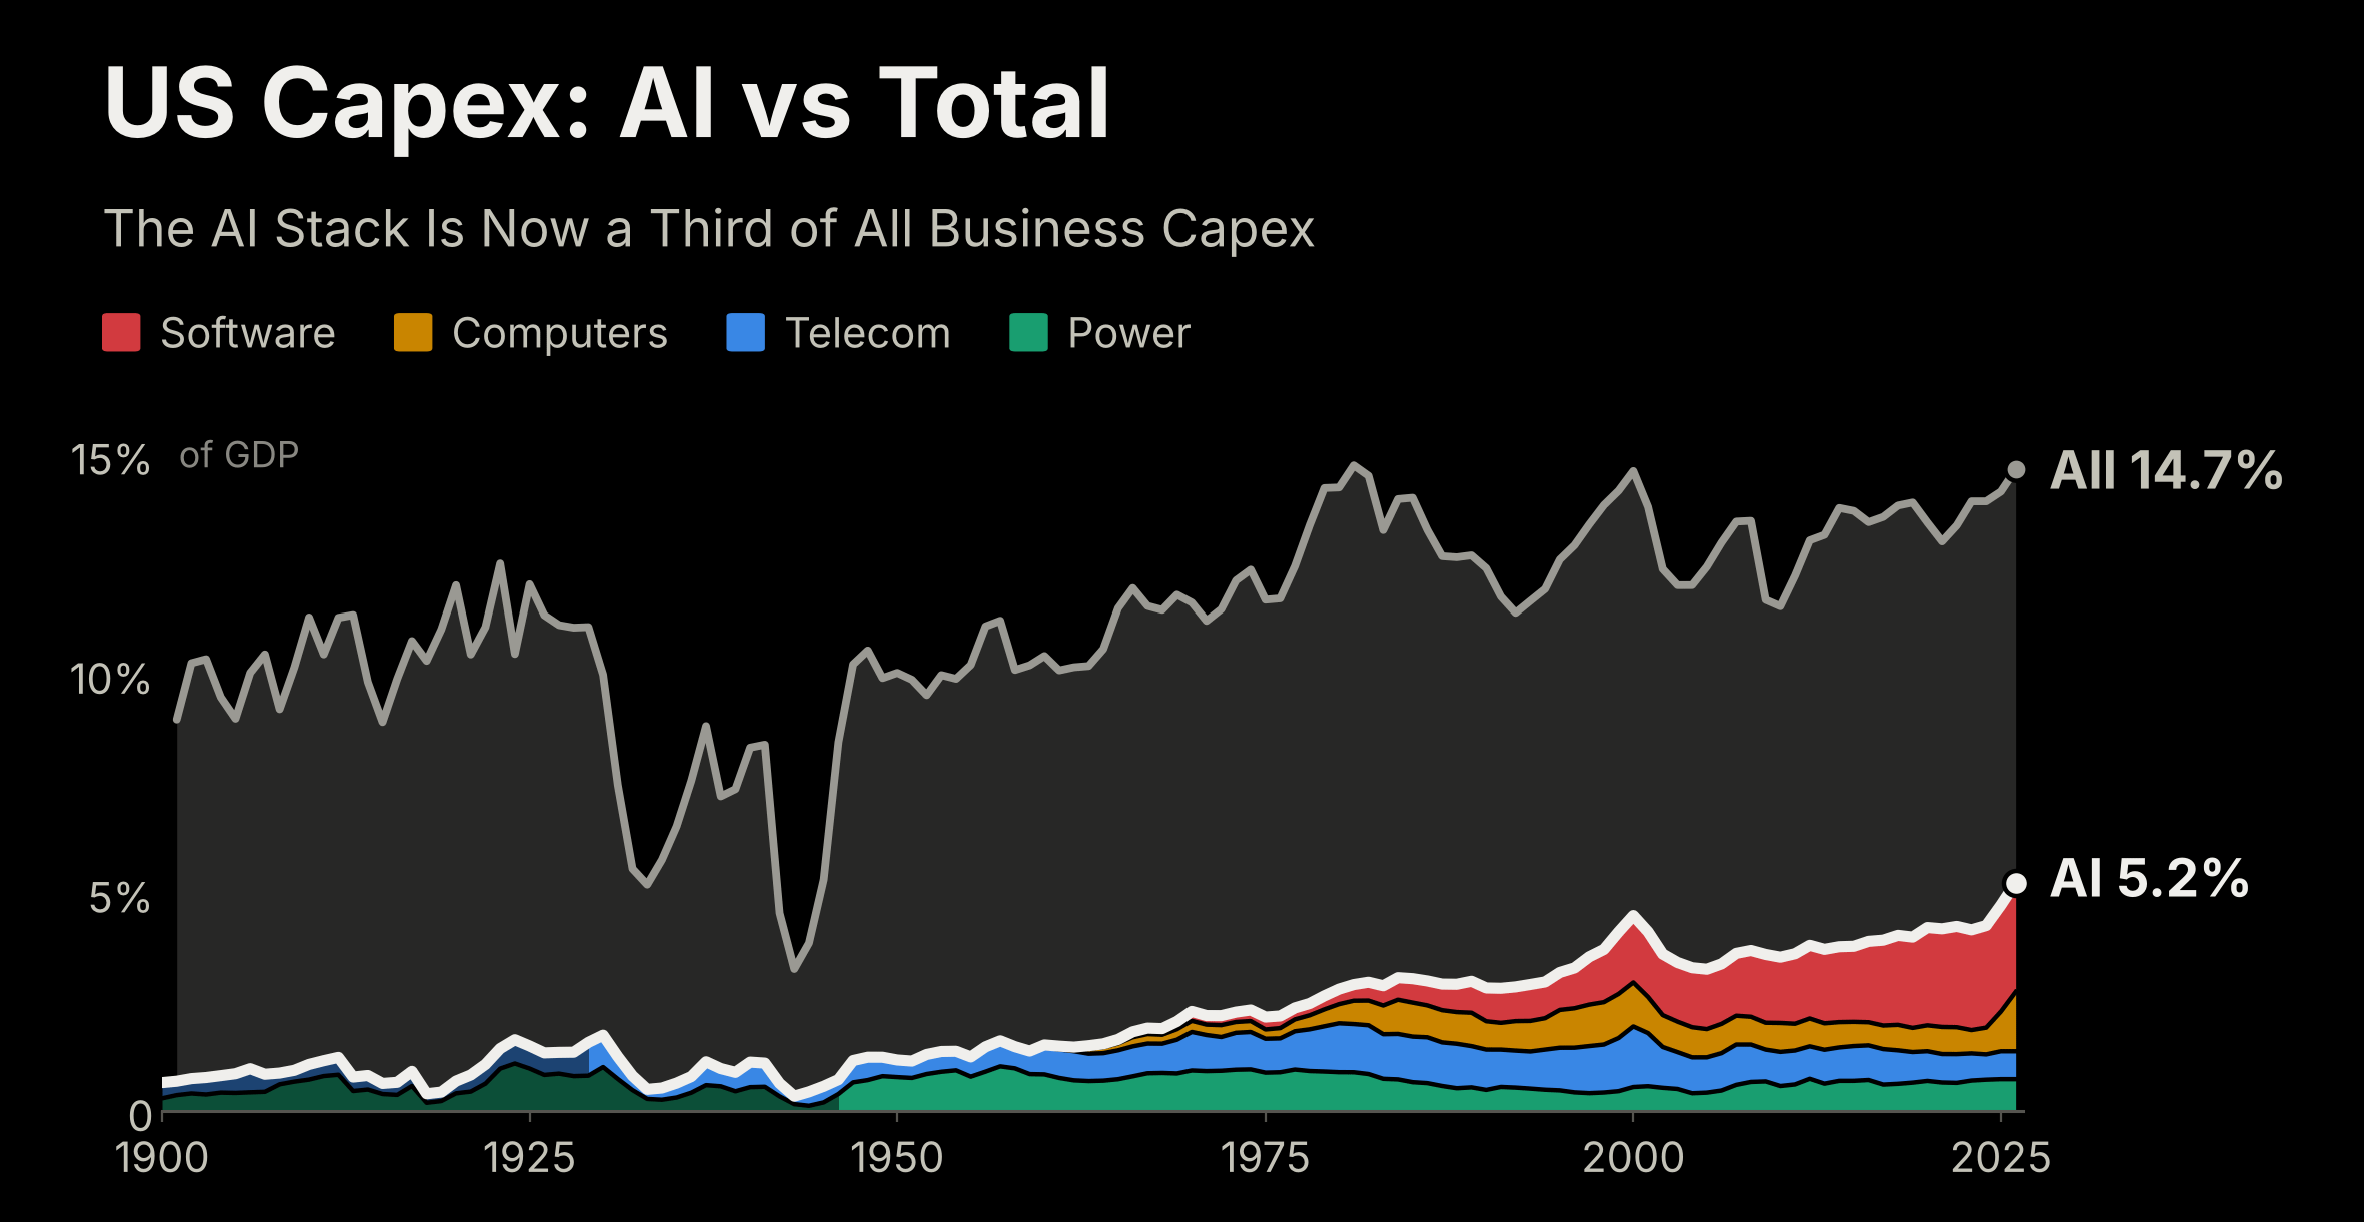
So yes, it’s possible that Fed tightening, combined with a peak in expectations, gives everyone a hangover. The AI stack is running at 5.2% of GDP, past the 4.5% we hit in 2000, and total business capex is back to 14.7%, tying 1981. The Fed was hiking both of those times too.

On the other side, most of these things impact token SUPPLY, not token demand. Demand seems healthy, and yes, a lot of it is VC-financed, but you can expect it to migrate to enterprises as they decide to own (or rent) their own stack.
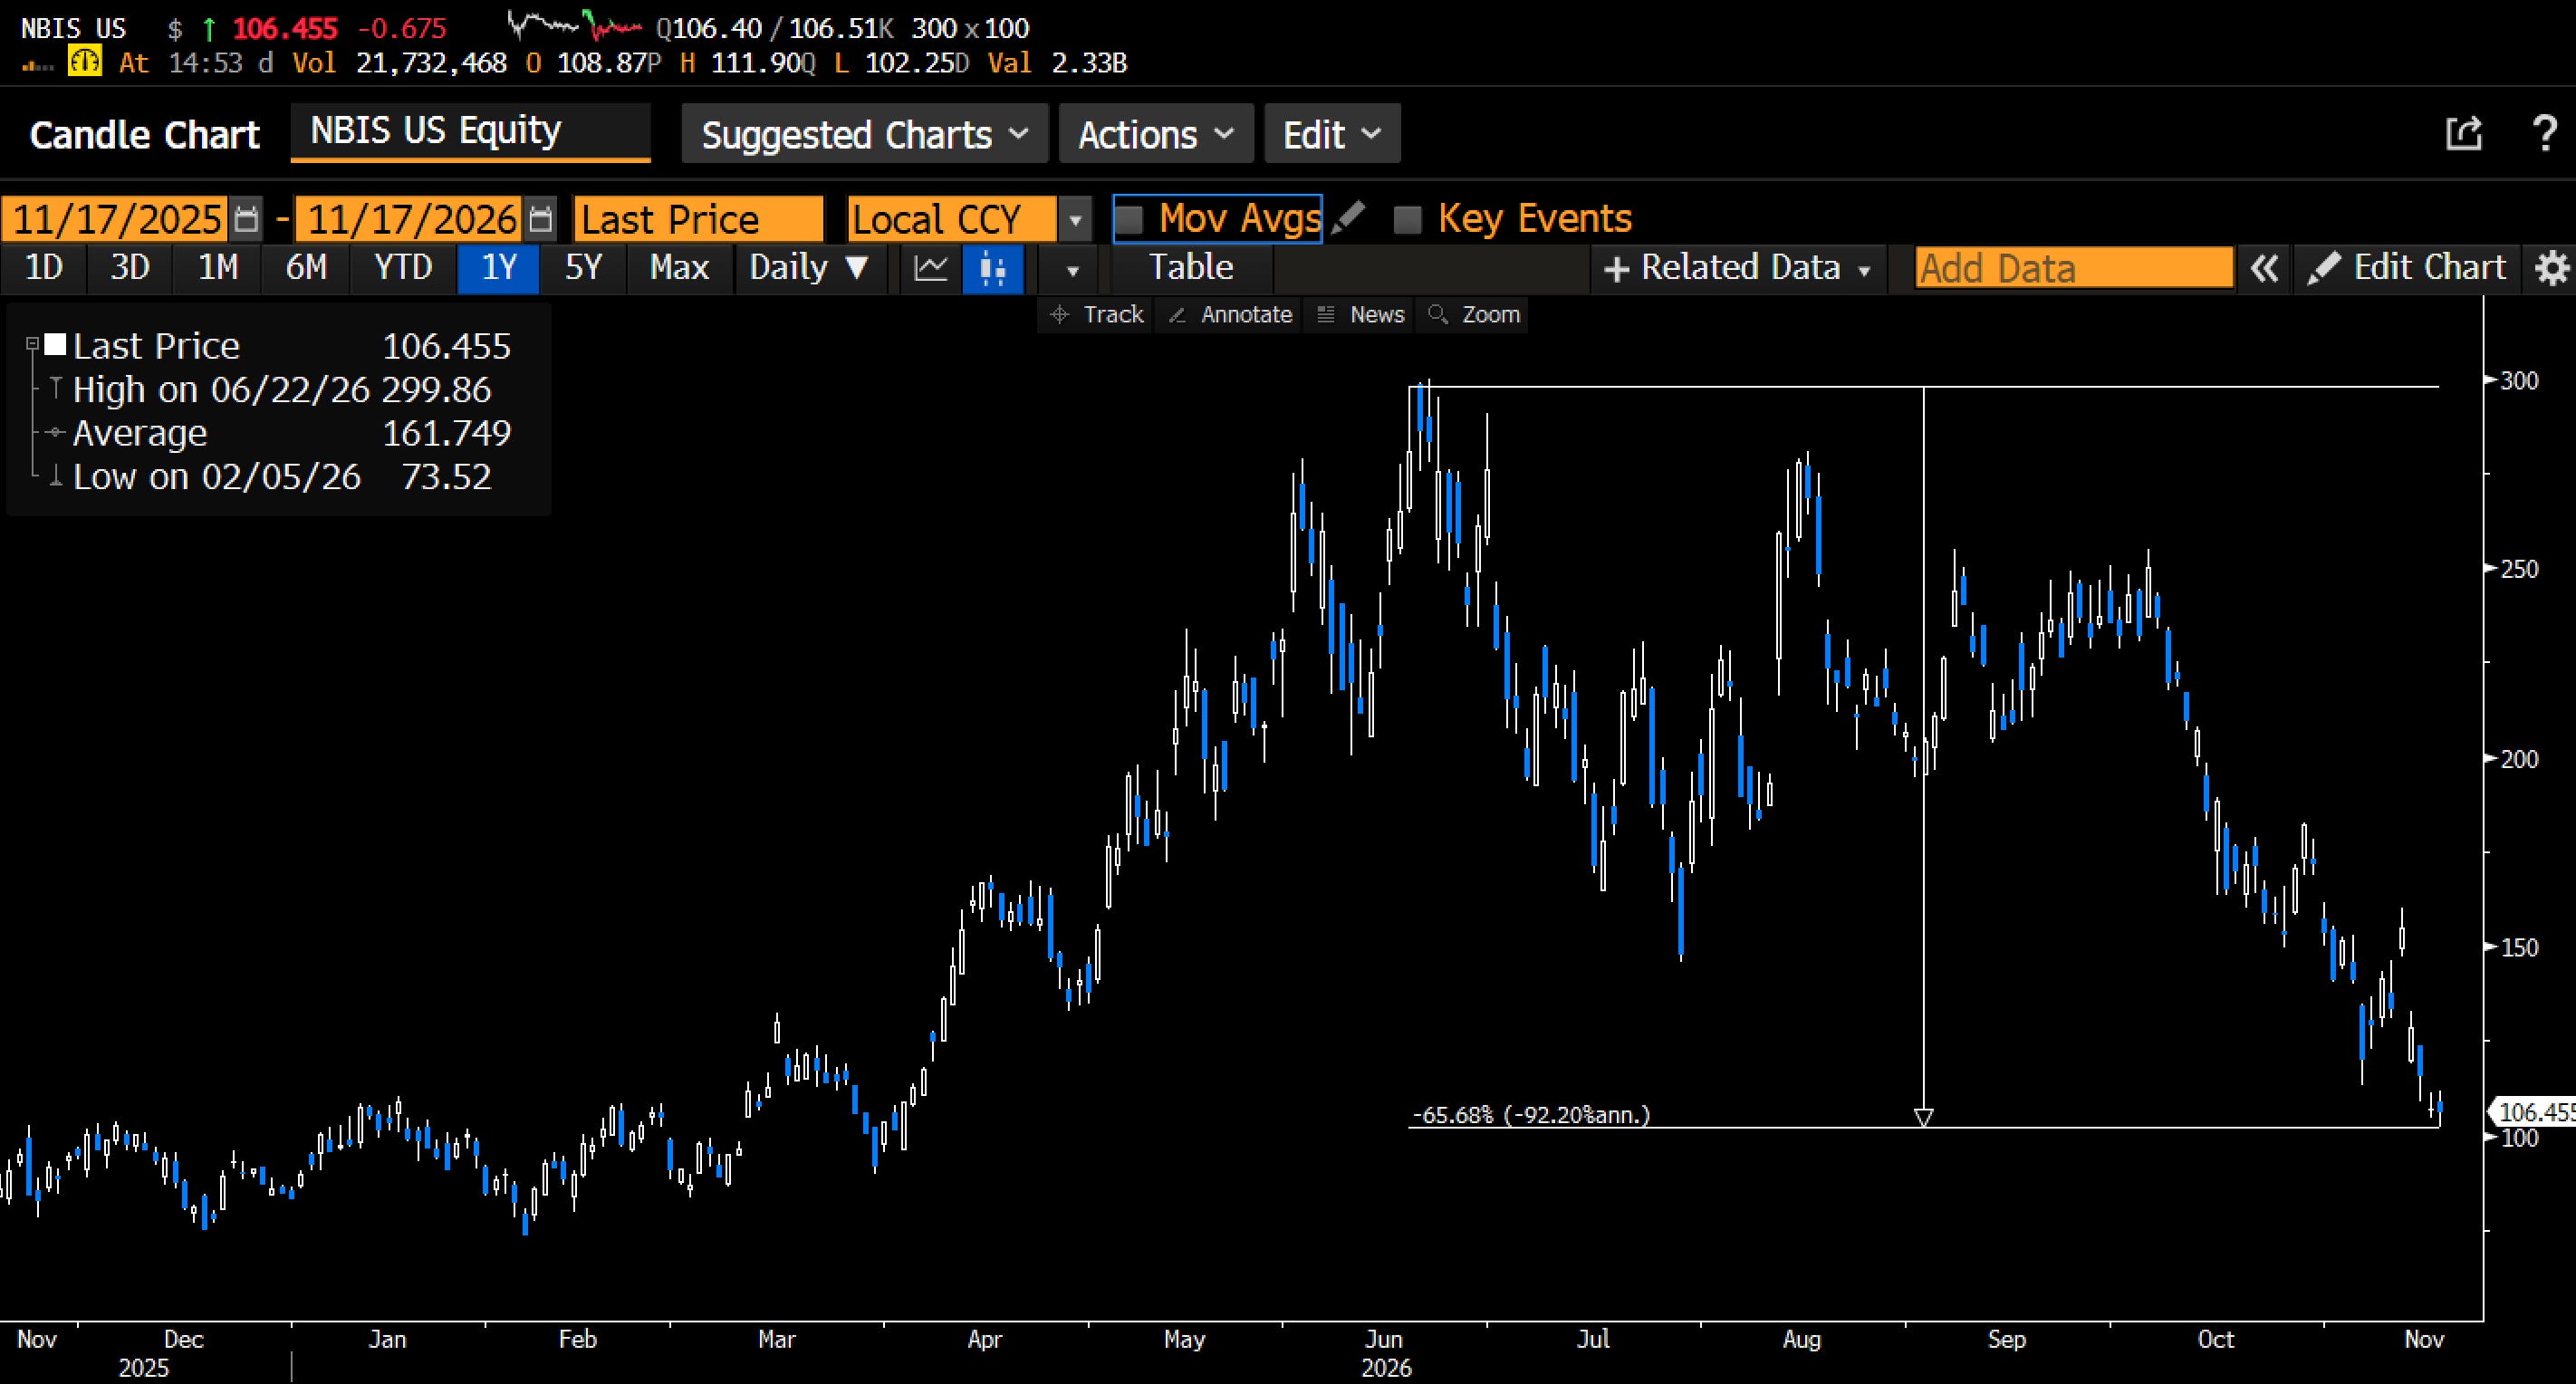
I, for one, went to the market this week to find some H200 compute, and none could be found outside of preemptible nodes out of Nebius. Which just so happens to be Leopold’s favorite neocloud. Props to the OG. I bought a bit this morning. The problem was never the theme, it was the risk control that led to 4x leverage on a 100% correlated portfolio of 50 vol names. I will take that informed dumpster dive, thank you very much.
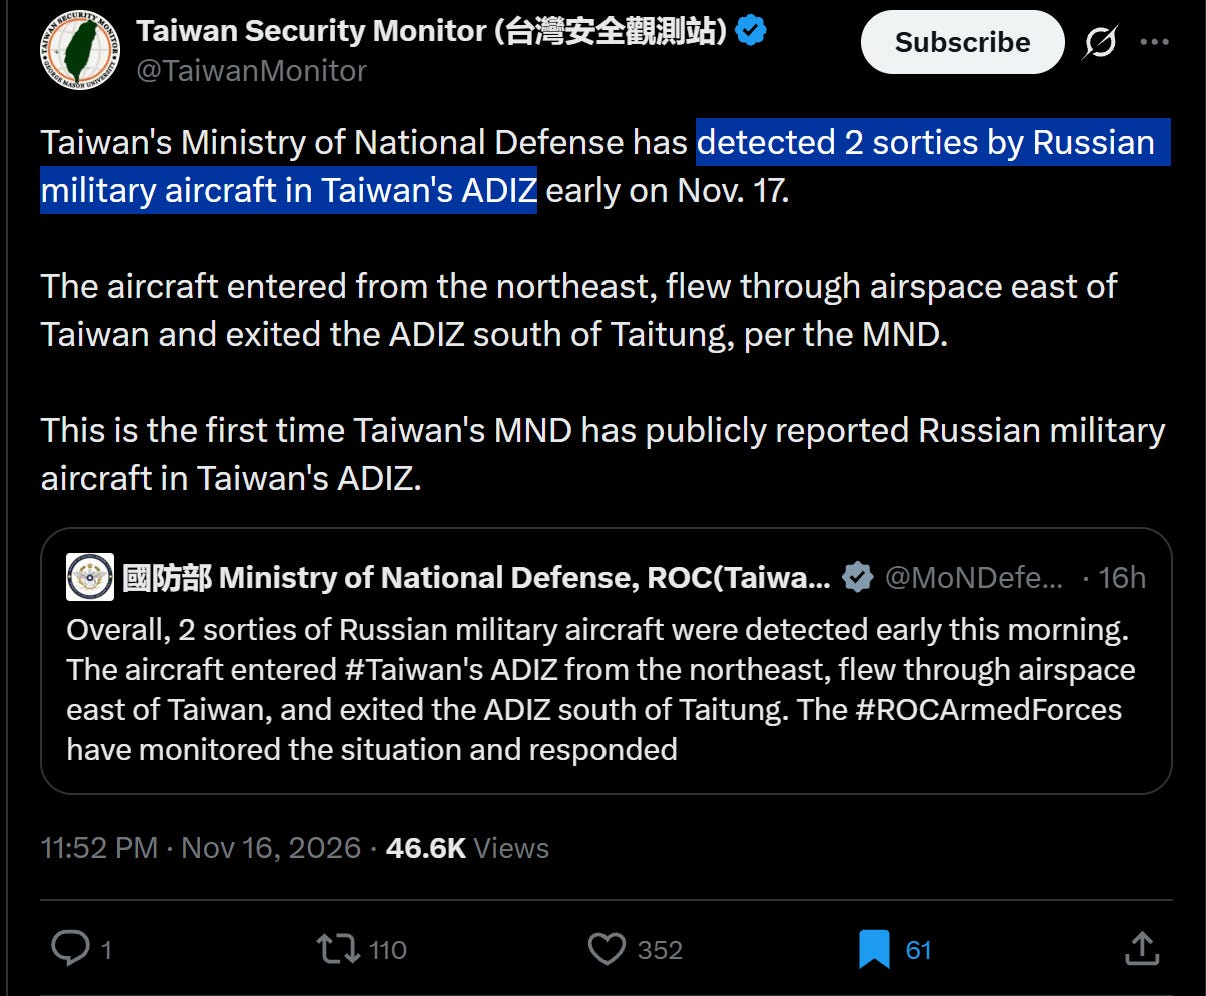
Meanwhile, the case for deglobalization builds.
Which isn’t a tight conclusion. We remain short stocks, we remain long minerals and compute (in more ways than one), and we are prepared, financially and otherwise, for things to get a lot weirder in the next six months.
Stay safe out there.
Till next time
I recall a year ago you were pushing silver. Then you never suggested when to exit. One way makes a reader very suspicious.