


Bonds and stocks in the news since we wrote about how many bonds are in the stocks.

Since the prior piece in May…stocks up, bonds down.

Bigly, as the kids say.
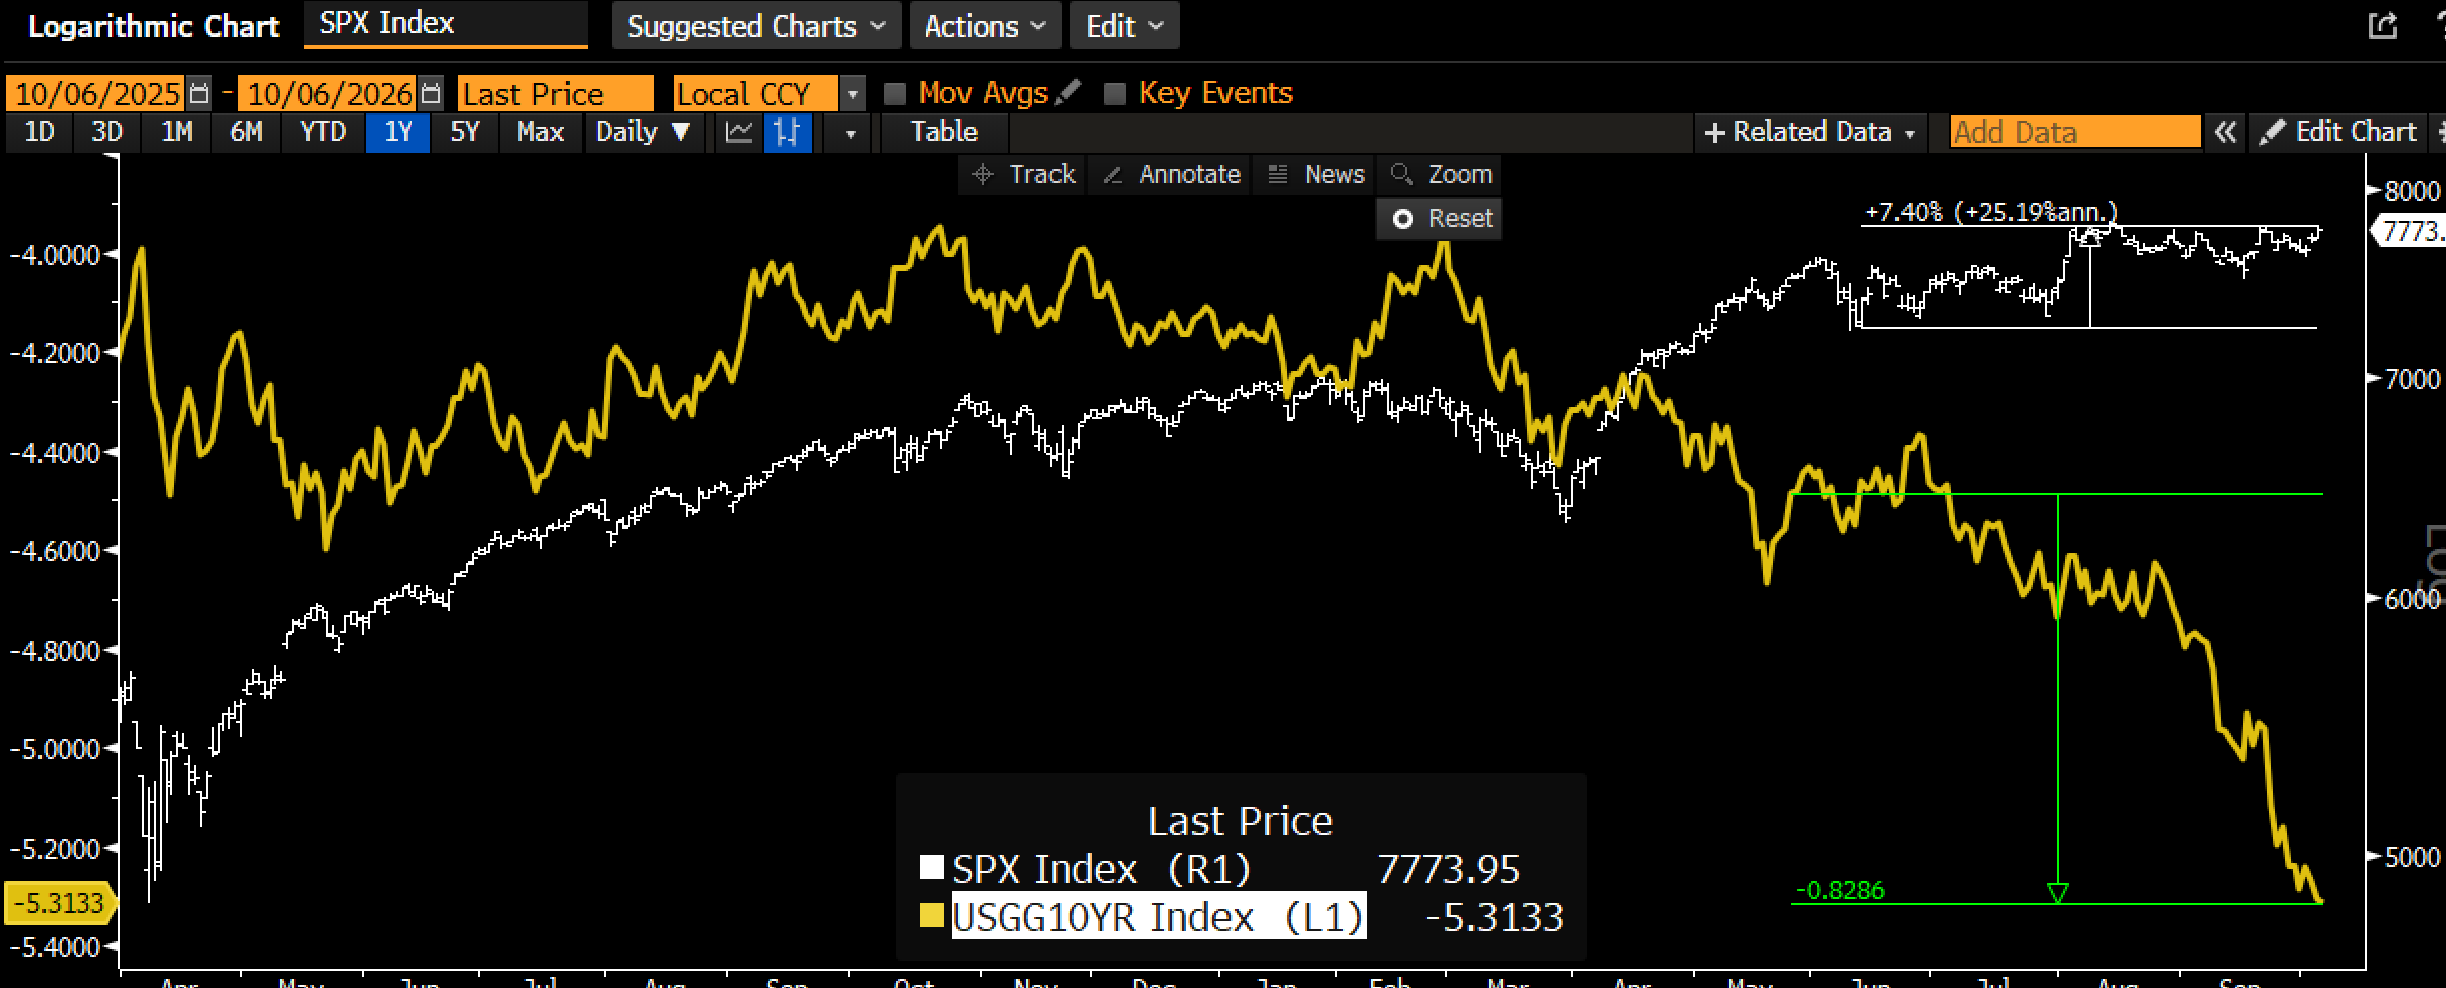
Remember, when you see stocks up, bonds down, it helps to reflect on the linkages this represents. Not as a story about the past, but about what markets (read: people) are pricing in for the future.
This is one of those concepts funds would patent if they could.
But this one is just logic.
Bonds are down, and bonds represent the common NPV effect of the future path of interest rates.
And stocks are not flat (which would be relative outperformance) but actually UP.
Which tells you the market is pricing in more growth, more earnings, enough to more than compensate in NPV space for the damage you just took from bonds.
The usual second leg is inflation. Earnings are nominal, coupons aren’t, so if the market is worried about inflation, stocks beat bonds. Except when you split the 10yr into its real yield and its breakeven, that’s not what happened.
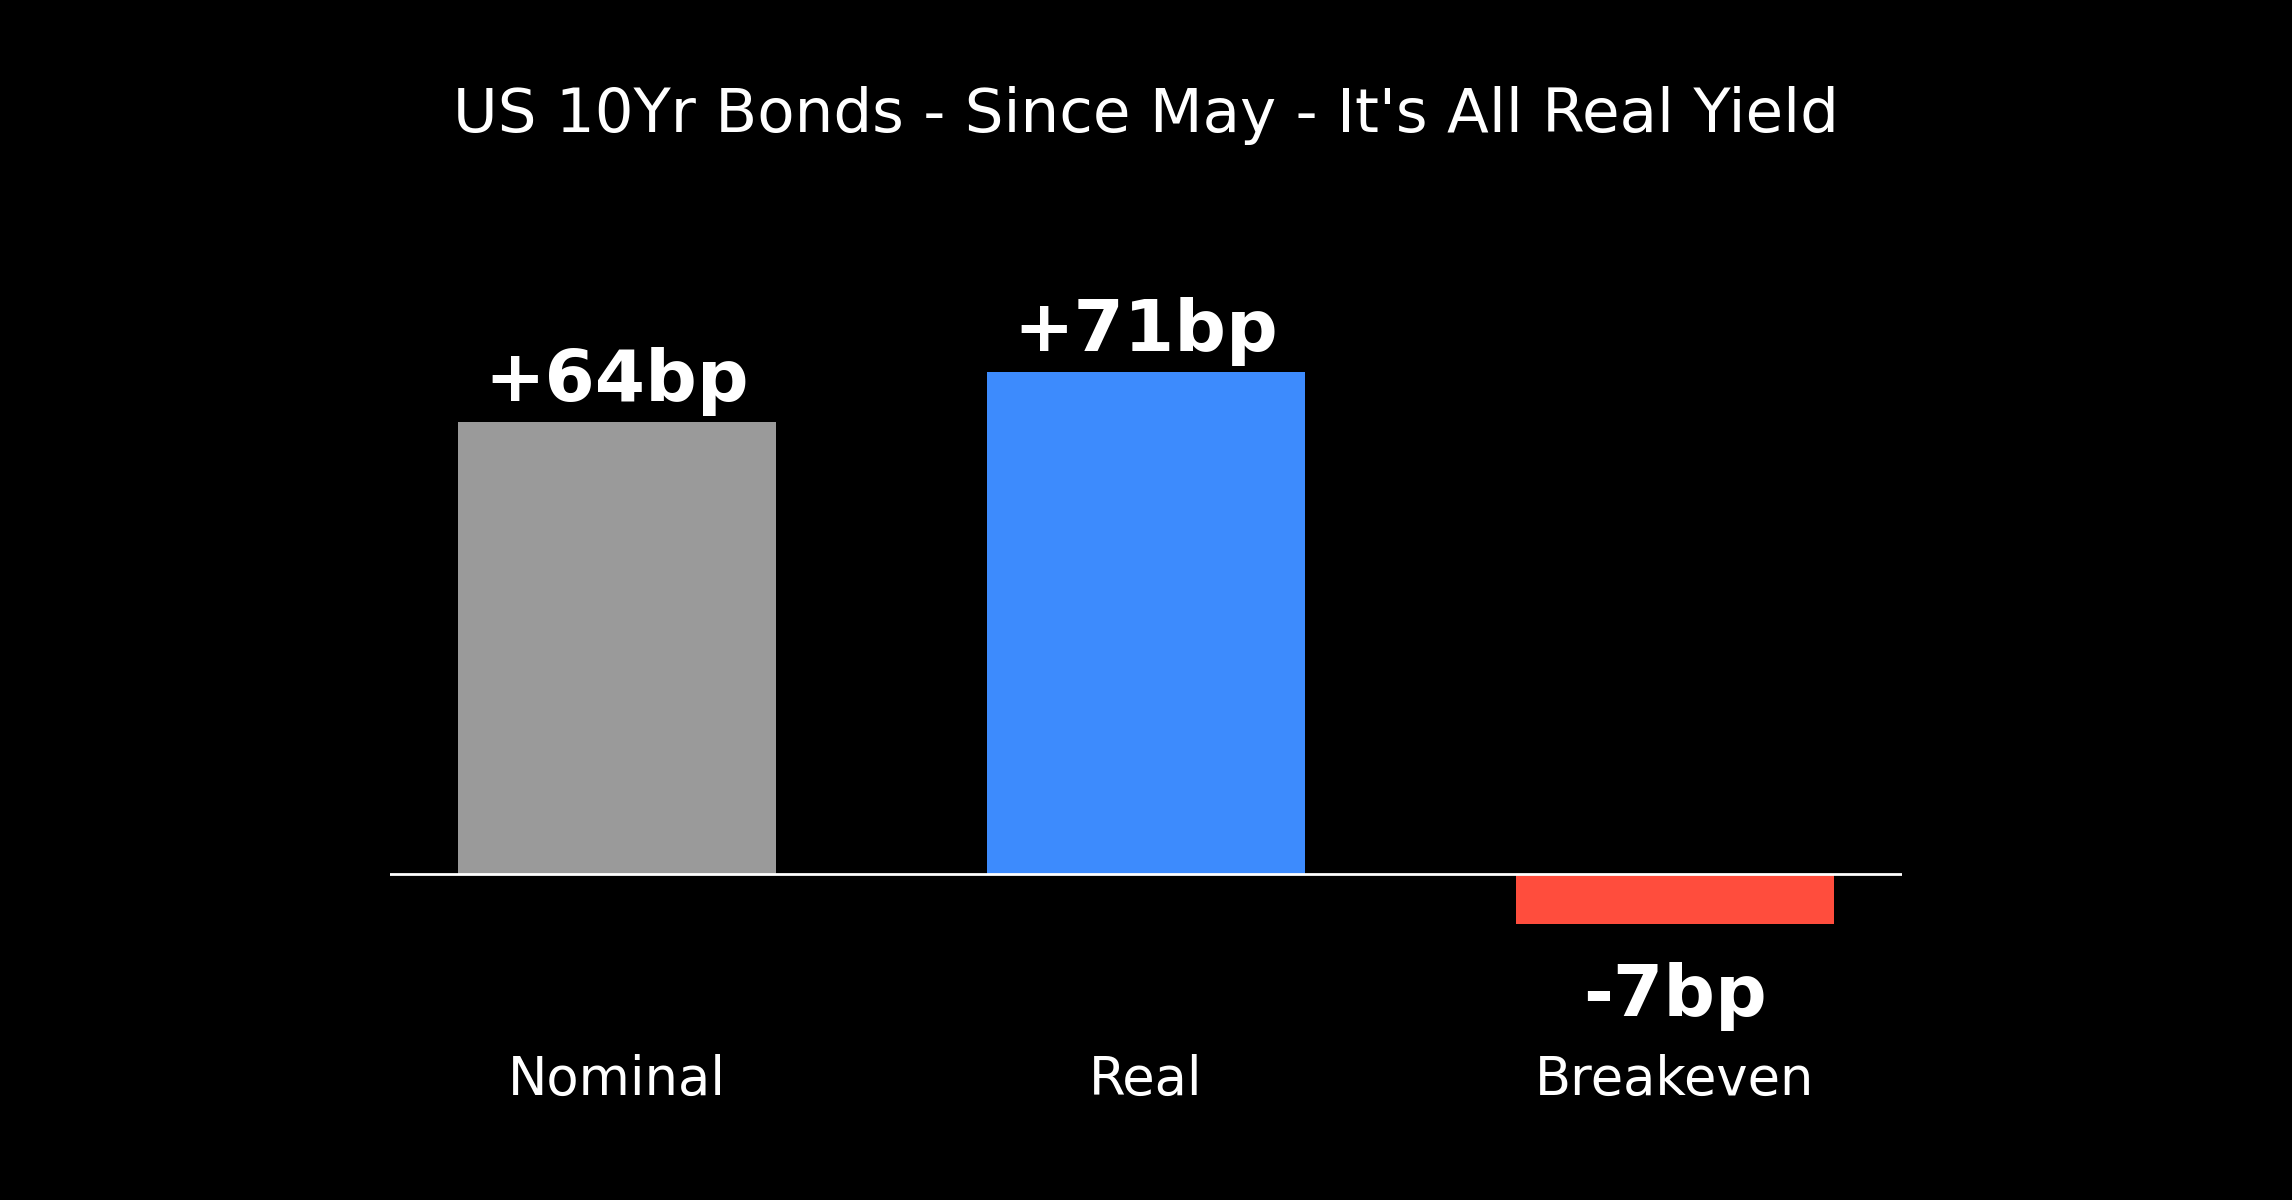
The whole move, and then some, is real rates.
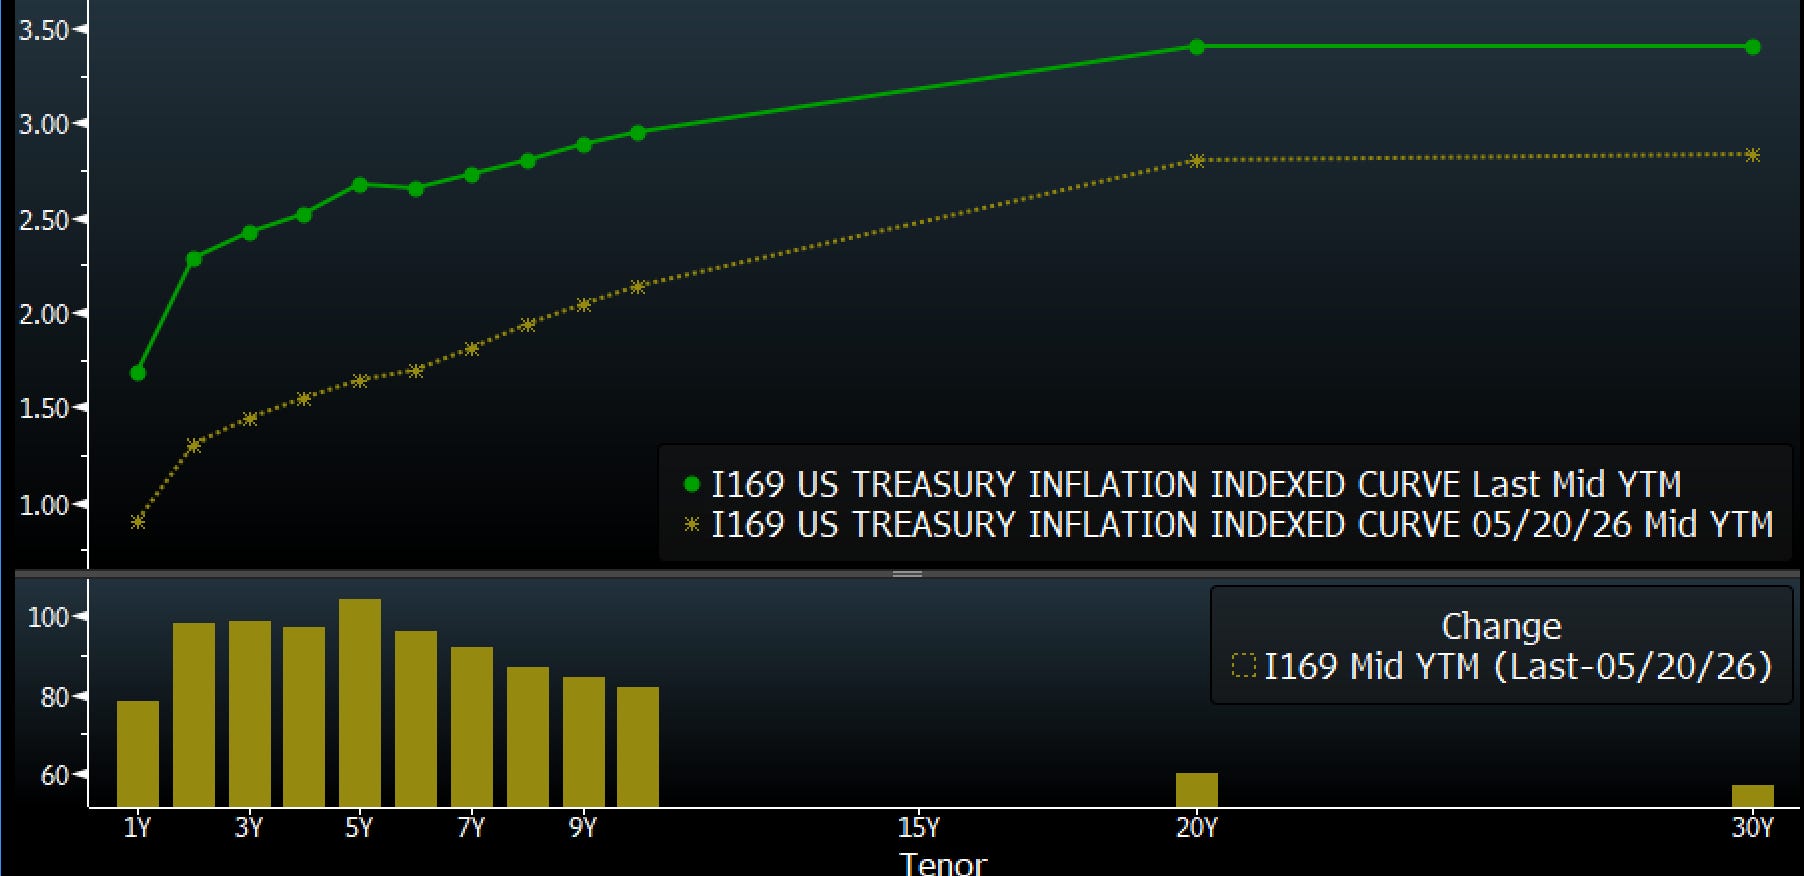
Breakevens are lower than they were in May.
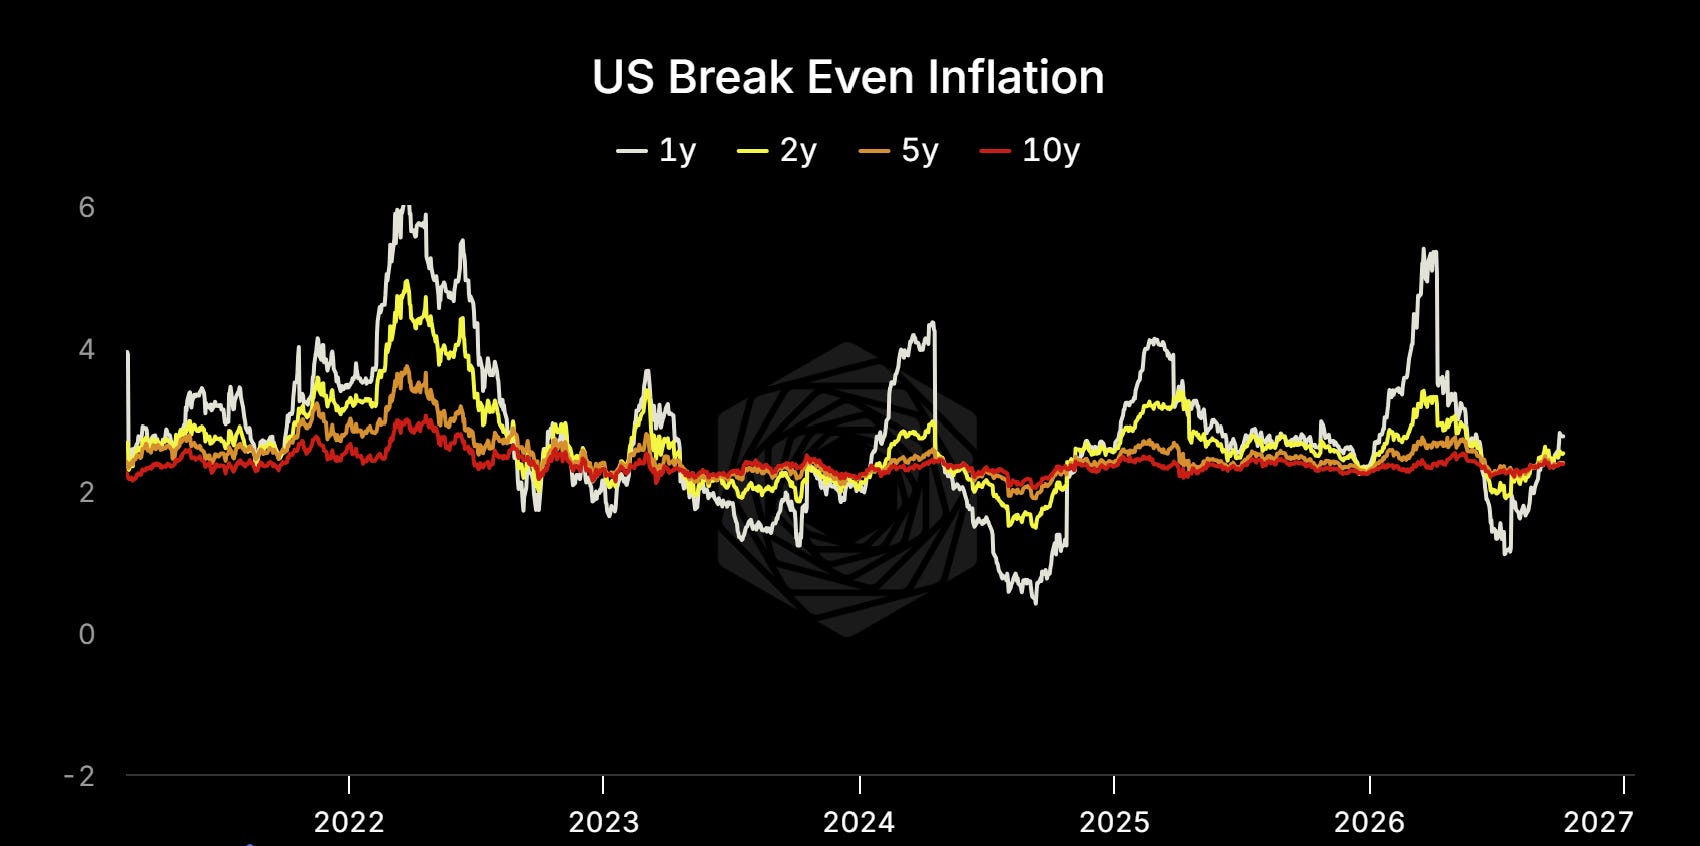
10yr real yields are at 2.88%, above where the October 2008 TIPS auction cleared in the middle of the GFC.
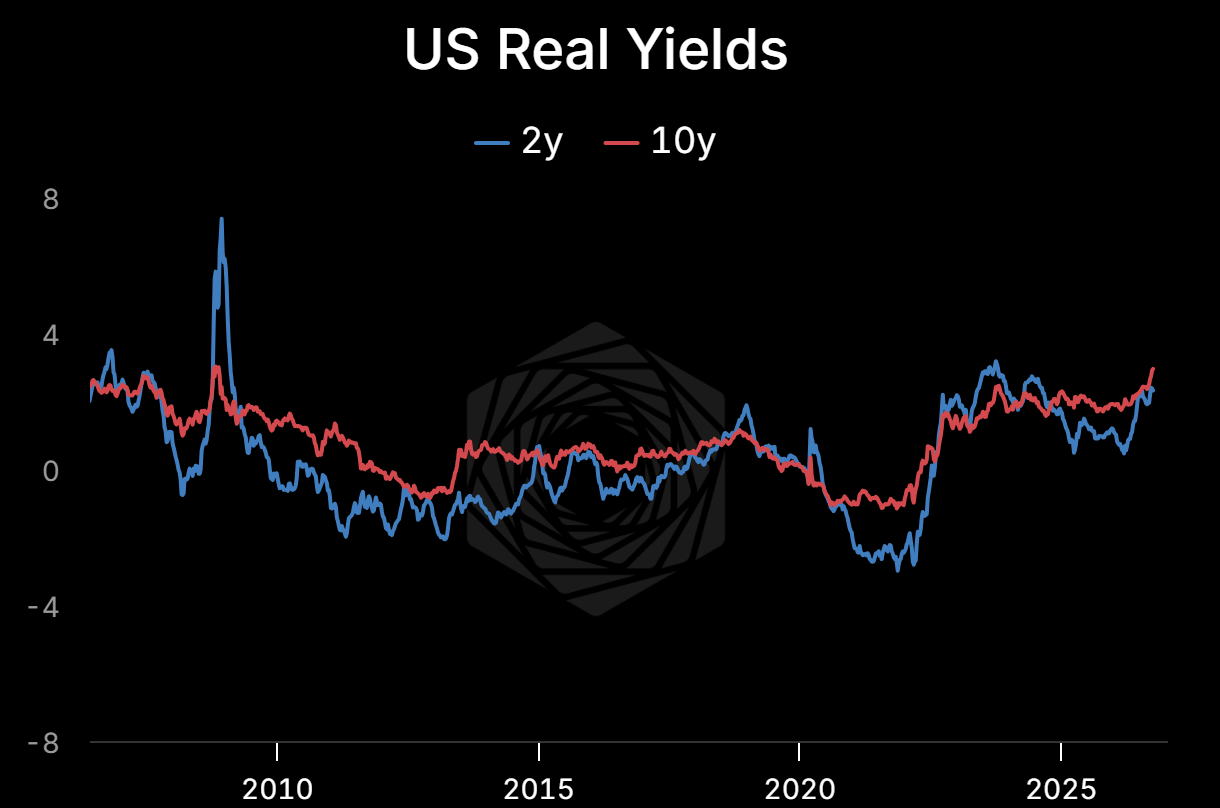
So the market is pricing a higher real cost of money, and stocks don’t care. That's the equity risk premium compressing in spite of higher real yields, aka higher P/E, aka more risk, as the engine of the singularity sucks up capital and puts it to work on NPV-positive AI capex.
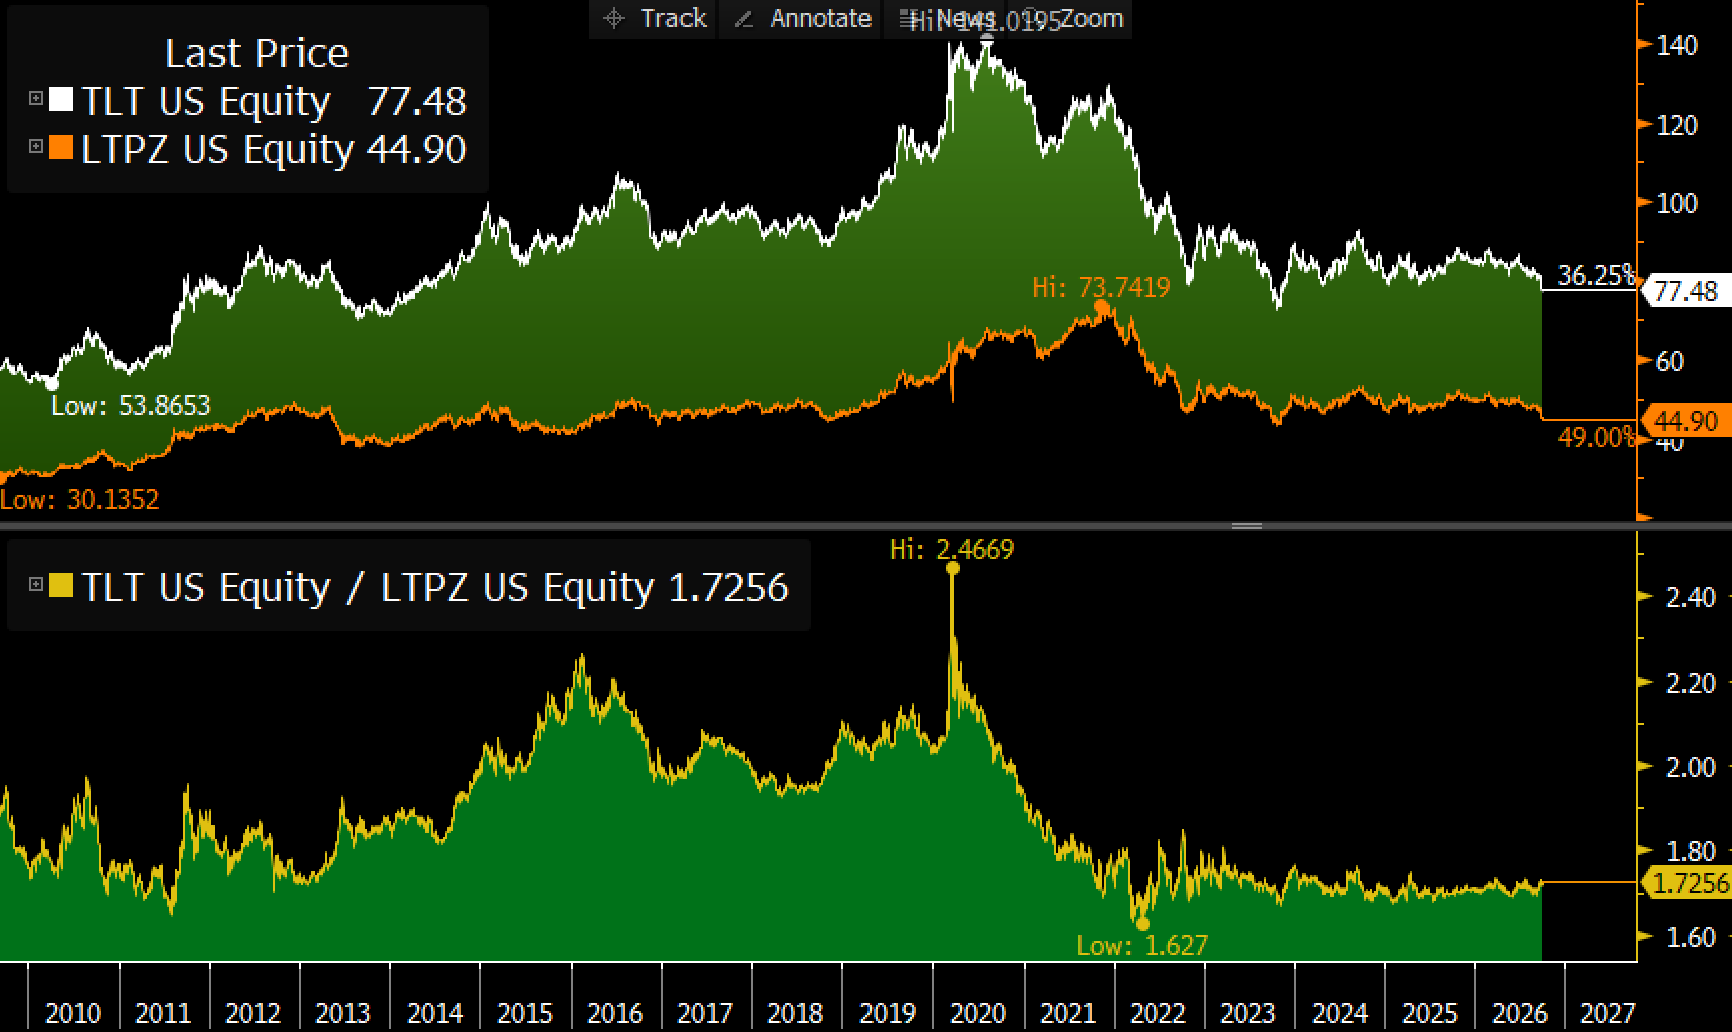
Which is why today I looked at buying calls on inflation linked bonds and then nominals. No liquid options on LTPZ, so it’ll have to be TIP and TLT or maybe even their ratio. Which, after all, was my widowmaker at Lehman. Turns out I was buying what Ray was selling even back in 08.
See, the ramble is going on something of a road trip, one might even say road show, with our newfound verbal freedom. The trip likely culminates some point in late October in an undisclosed sunny location, where we will hopefully get enough time in one place to let the machine start trading markets. Barring that, at least content farm a bit by watching me try and fail to make machines manage machines, and all that entails. Cue the "machine is down, don't trust machines" cycle you all know and love.
Which is a long way of saying, yes, I know you would like us to start a big complicated portfolio asap and run it day to day, but we’re going to do the opposite. Going slow, starting with beta, which was last week’s LTPZ transaction.
Today we looked into medium length options, and when we checked the markets, 3:1 for March optionality on a ~8% rally seems a bit expensive.
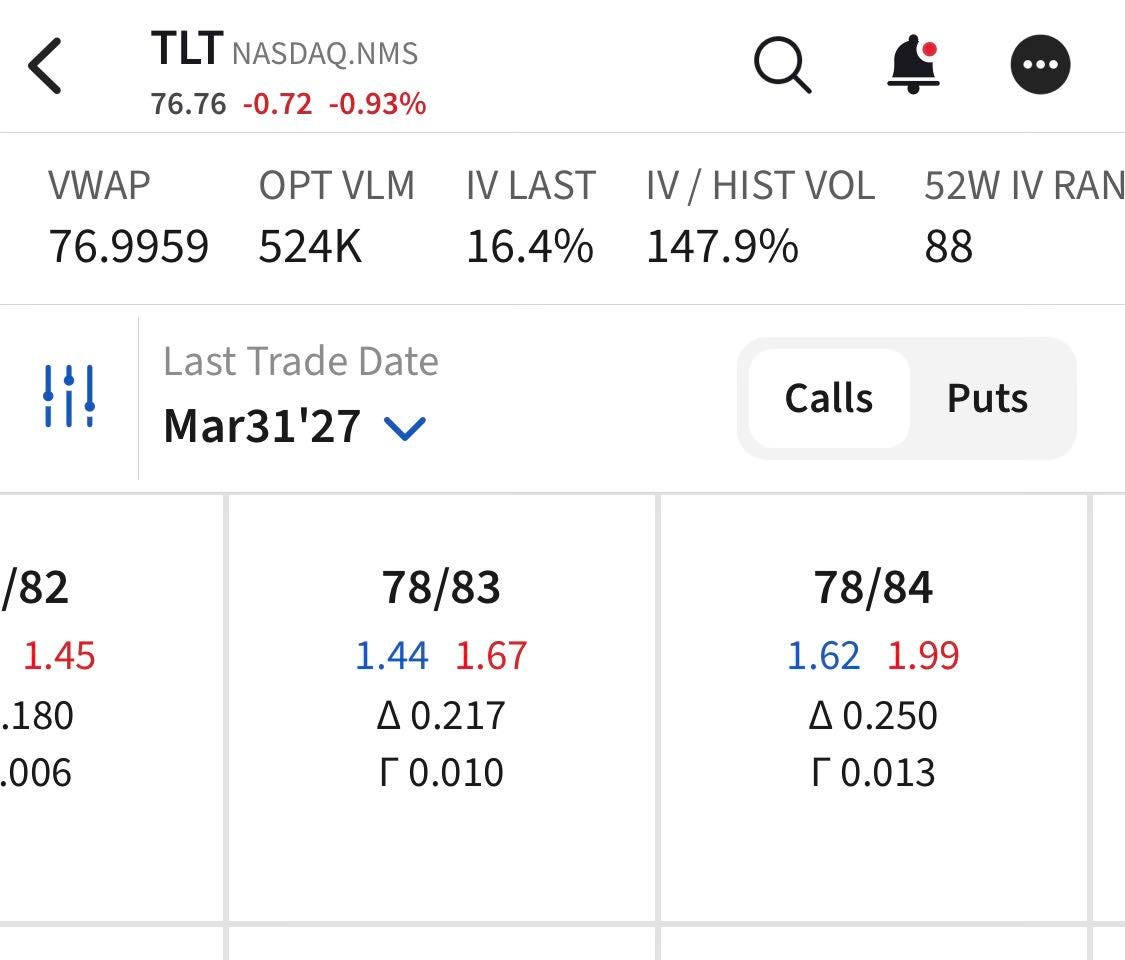
So we bought a tiny bit of nominal bonds (TLT) and gold (GLD) as ways to start up the beta portfolio and get a feel back for what the market is pricing in. We’re rebuilding All Beta, and you start with what you know and understand the risk of, the stuff you feel comfortable adding risk to or taking it off. A friend is recommending options but the ETFs looked expensive, so at some point we’ll go hunting for some convexity in more esoteric forms.
Additionally, in the coming weeks, we’ll do some combination of updating, scoring and tracking some of our earlier work. Here’s a preview, from an experiment lighting tokens on fire a while back.
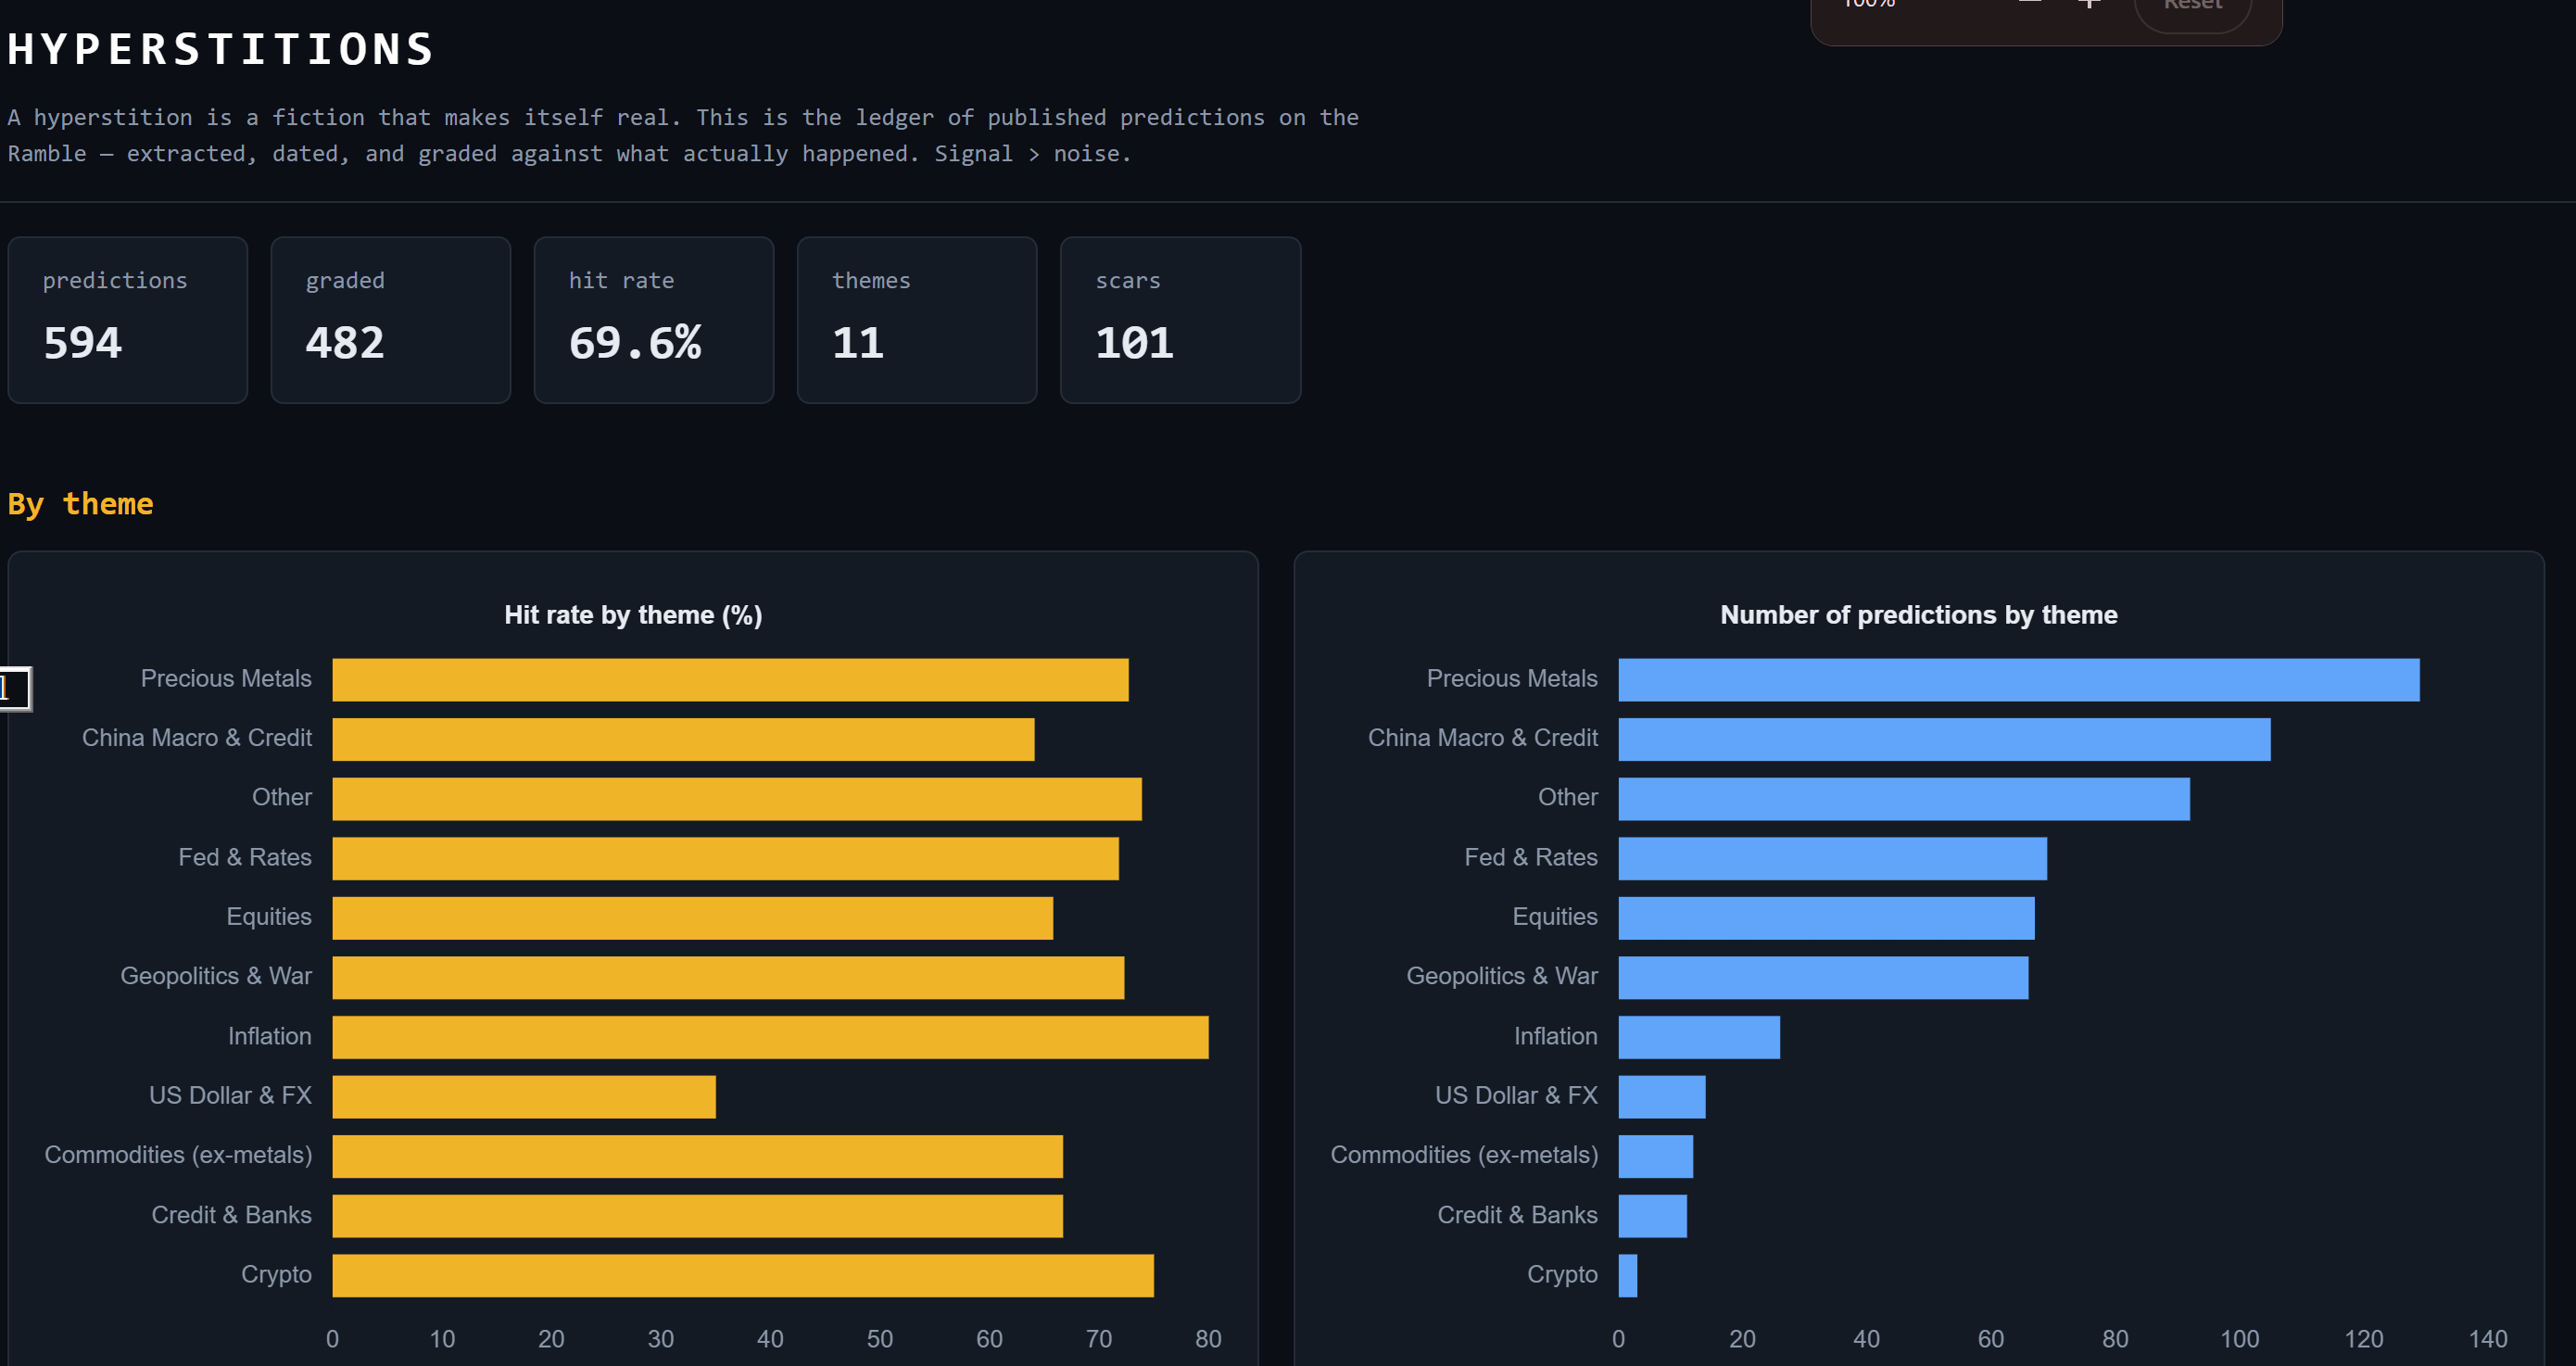
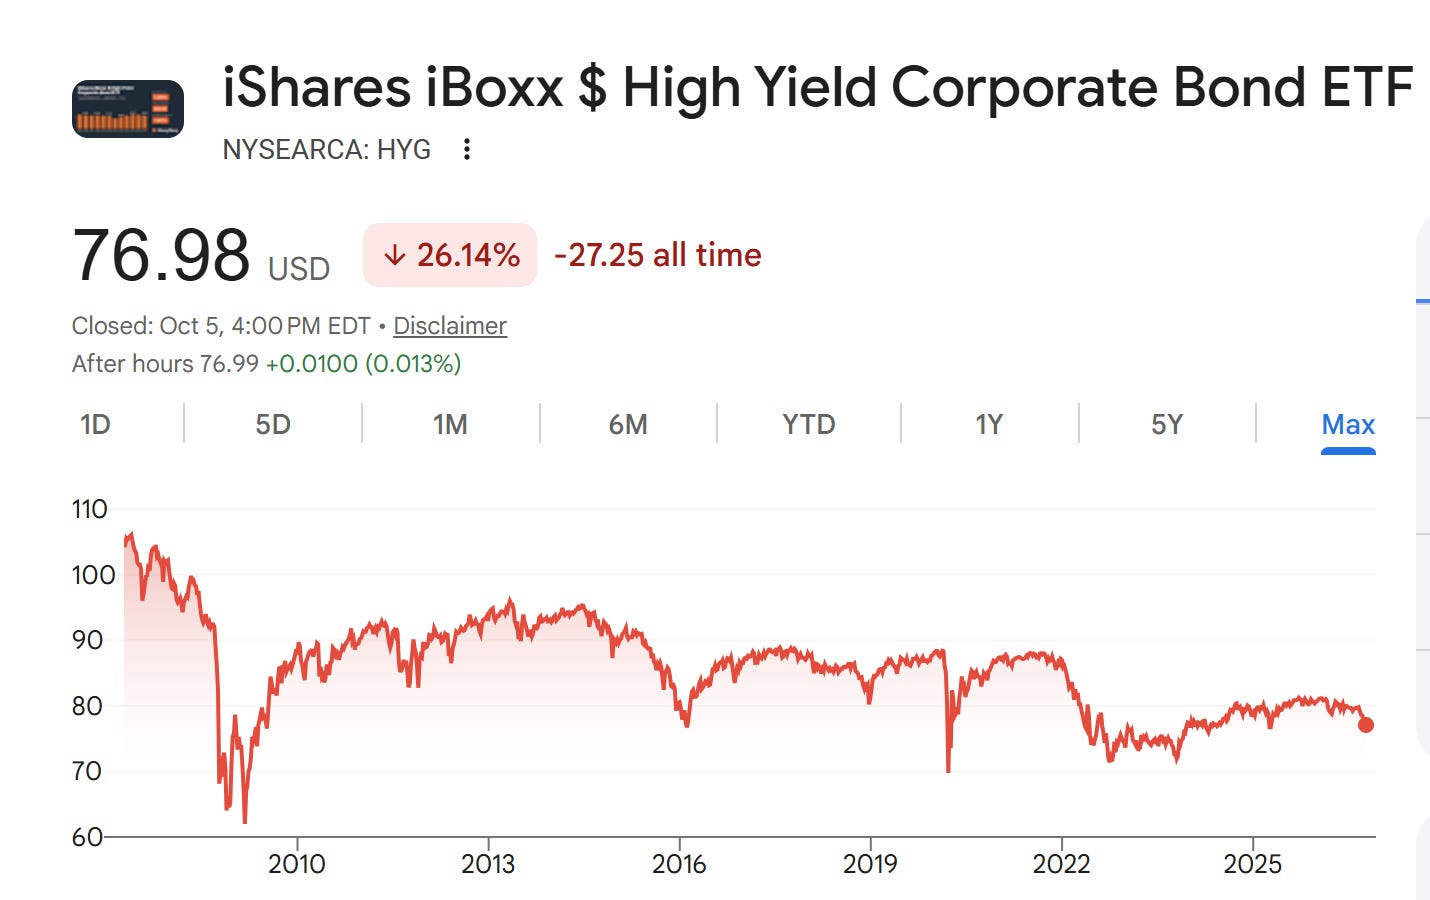
Finally, remember our most precious learning on how to time the end of the cycle:

Watch credit. Or rather, wait for it to rally and sell into the strength as a way to get short with leverage.
I wonder what "curve caps" look like (options on the spread between two points on the swap curve)…Alas, my kingdom for an ISDA. Bet there’s 20:1 out there for someone to pick up with a little creativity…
To be clear, are you trying to build a beta portfolio, along the lines of what you'd proposed in https://www.campbellramble.ai/p/whatever-happened-to-alpha-redux, but doing so opportunistically, one component at a time? And the alpha positions will follow? I have to admit, I've struggled to follow what the aims are since you've returned... the previous post referenced a strategic allocation and an illiquids book, the current post contains some cryptic comment about systematic trading(?). Some clarity on the overarching goals would be welcome.
1) Ray was more right than most people. However my lived experience has taught me:
- all betas are not “about 0.25”. Really it’s only equities and credit (and that’s a crappy payoff structure and basically an equity derivative) that have a structurally positive betas. And that’s because there is a clear “who’s bribing whom to put on the trade”. In other asset classes there are so many non economic fund flows that experienced betas are way less. Maybe another way of saying this is diversification is more priced in than we think
2) you can pick up a good amount of sharpe improvement via cheap equity tilts.
3) correlations move close to 1 far more often than risk parity implicitly assumes. The regime distribution is right in a general risk on or risk neutral environment but not anywhere near always.
Maybe the current 3.3% yield on 20 year TIPS which makes absolutely no sense to me is reminder that maybe the world works differently than we think.